Member Brief: The Huberman Effect

Temporarily Unlocked For The HBS “Optimization Chat.” In 1964, a Canadian-funded expedition led by Montreal physician Stanley Skoryna sailed to Rapa Nui (Easter Island) to conduct an unprecedented ecological survey of its biosphere led to the discovery of rapamycin, launching an enduring field of biomedical research. Known by the science community as a life-altering, life-extending drug, “Rapamycin is the most effective known cancer-preventive agent in mice. It has even been suggested that rapamycin extends lifespan by preventing cancer.” (NLM)

The drug is known to mimic calorie restriction. It works by inhibiting mTOR. mTOR sends signals to cells affecting growth, metabolism, and autophagy (a process that clears old cells in favors of new ones). How do I know any of this? And why do I even care? I am certainly not alone.

Ask ten college-bound students with top-percentile ACT scores what they plan to major in and you may hear “neuroscience” or any other biological science. I would guess that you would hear this more than you would have a decade ago, when that same student may have replied with “computer science” or “engineering.”

Let’s call it the Huberman effect.

The dawn of the 21st century has witnessed an ever-increasing focus on personal wellness and optimization. This trend, fueled by technological innovation, a renewed interest in hyper-healthy foods and an influx of digital health and wellness brands, is transforming the health industry. Companies like Whoop, Eight Sleep, Apollo Neuro, Base, Oura Ring, and Apple, with its highly successful “Ultra” version, have paved the way for this new era of human optimization.

You may have also heard of Brian Johnson. He’s the entrepreneur who sold his company Braintree to Paypal for $800 million and then devoted his life at 45 to various methods of age reversal, attempting to shed his biological age down to 18 years. He’s wealthy, obsessive, driven, and uniquely focused on his own body. He’s not the only one (though his methods may be extreme). From a January 2023 Bloomberg BusinessWeek article on the anti-aging pioneer:

This year, he’s on track to spend at least $2 million on his body. He wants to have the brain, heart, lungs, liver, kidneys, tendons, teeth, skin, hair, bladder, penis and rectum of an 18-year-old.

There’s a collective of data points that suggest the “Medicine 3.0” craze has provided tailwinds for an array of health-focused companies. Medicine 3.0 is a highly-personalized stage of sophistication in healthcare that we are accelerating towards. It’s predicated on “evidence-informed” as opposed to “evidence-based” guidelines around preventative measures for chronic conditions, which are now “the dominant source of morbidity and mortality.”

The growth of Restore Hyper Wellness is a testament to this trend. Founded with the mission to make wellness treatments more affordable and accessible, the company has expanded rapidly, offering a broad range of services, including cryotherapy, IV drip therapy, and hyperbaric oxygen therapy. They have democratized access to wellness treatments, typically reserved for professional athletes and the wealthy, to the general public. This shift has been instrumental in empowering individuals to take control of their wellness journey.

In parallel, a new breed of educators and influencers has emerged, with podcasts and digital platforms to spread awareness and knowledge about personal health optimization. Lex Fridman, an AI researcher at MIT, hosts a podcast known for deep, thought-provoking conversations on AI, mindfulness, and human potential. Dr. Andrew Huberman, a neuroscientist and tenured professor at Stanford University School of Medicine, shares his deep knowledge about the brain and its impact on our behavior and well-being. Dr. David Sinclair, a professor in the Department of Genetics and co-director of the Paul F. Glenn Center for the Biology of Aging at Harvard Medical School, explores the science of aging and longevity. Finally, Dr. Peter Attia, a former surgical oncology fellow at Johns Hopkins Hospital, focuses on the science of longevity, nutritional biochemistry, and exercise physiology. Their collective influence has been instrumental in driving a cultural shift towards proactive, preventative health.

Simultaneously, we are seeing a reemergence of interest in hyper-healthy consumer packaged goods retailers. This trend is not about fad diets but about embracing nutrient-dense, whole foods that support optimal human function. Companies like Heart & Soil, Force of Nature, and ButcherBox are leading the charge in this space, delivering high-quality, grass-fed meats and organ meats, known for their dense nutrient profiles, straight to consumers’ doors. The popularity of these brands reflects a broader societal shift towards transparency, sustainability, and nutrient density in our food choices.

On the accountability front, wearable technology like Whoop, Eight Sleep, and Apple Ultra are playing a crucial role. These devices provide real-time data on a range of health markers, including sleep quality, heart rate variability, and physical activity. This personalized data empowers individuals to make informed decisions about their lifestyle and habits, reinforcing a culture of accountability and personal responsibility for health. Whoop, for instance, offers insights into recovery, strain, and sleep, enabling users to optimize their daily routines for peak performance. Apple’s Ultra wearable takes it a step further, integrating health tracking with a broader ecosystem of apps and services designed to support overall wellness.

The proliferation of eCommerce brands in this space is another critical aspect of this emerging industry. Companies like Thrive Market and Misfits Market are not just selling products; they are selling a lifestyle. They provide consumers with the insights they need to take control of their health, whether it’s high-quality, nutrient-dense foods, supplements, or wellness products. These companies are thriving because they align with the values and priorities of a growing segment of the population that is actively seeking ways to optimize their health and performance.

Human optimization is no longer a niche interest, but a full-blown cultural and economic trend. As we enter this new era, we see the intersection of technology, education, personal responsibility, and a renewed focus on the quality of the food we consume.

The data-driven insights offered by wearable technology are not just changing the way we approach fitness and health; they’re altering our perception of what is possible. With these tools, we are no longer passive recipients of health advice but active participants in our wellness journeys. This is one of the core tenets of prevention that Dr. Peter Attia espouses when referencing Medicine 3.0. For a deep dive, read his new book Outlive. There are endless nuggets like this one:

[Rapamycin’s] autophagy-promoting effect is only one reason why rapamycin may have a future as a longevity drug, according to Matt Kaeberlein, a researcher at the University of Washington. Kaeberlein, who has been studying rapamycin and mTOR for a couple of decades, believes that the drug’s benefits are much more wide-ranging and that rapamycin and its derivatives have huge potential for use in humans, for the purpose of extending lifespan and healthspan.

Summary

The education provided by influential figures in the realm of health and wellness is democratizing knowledge that was once confined to academic and clinical circles. The podcasts of Lex Fridman, Dr. Andrew Huberman, Dr. David Sinclair, and Dr. Peter Attia have made complex health, fitness, and longevity concepts accessible to the masses, sparking a widespread interest in personal optimization.

The resurgence of hyper-healthy foods underscores a collective reevaluation of our dietary choices. This shift is not just a rejection of processed, nutrient-poor foods but an embrace of those that provide us with the nutrients our bodies need to function optimally.

And the success of eCommerce brands in this space reflects a growing demand for products and services that support this optimization-focused lifestyle. These brands are not merely selling goods; they are providing the tools, resources, and community needed for individuals to take charge of their health.

The emergence of human optimization as a major industry underscores a profound shift in societal values and priorities. It speaks to a collective desire to not just live longer, but to live better. As more individuals strive to reach their full potential, companies, educators, brands, and services are rising to meet this demand, paving the way for a healthier future for a higher percentage of our citizens. This paradigm shift, driven by technological innovation, education, and a renewed focus on quality nutrition, is just the beginning of what promises to be a transformative journey towards optimized health and wellness. And to think, this resurgent interest in anti-aging methods may have all started with visits to the mysterious Easter Island. No, not the one in 1964. The ones where Dr. Peter Attia joined Tim Ferris and a rotating group of science-loving buddies.

By Web Smith | Edited by Hilary Milnes with art by Christina Williams
Memo: The New Evangelism of Prime Access

If you grew up with a frequently empty-ish refrigerator, Amazon Prime is a godsend. As an adult: you wake up, look at your refrigerator, your memories drive an irrational response, and you needlessly open an app to fill the empty spaces in your pantry or cold storage. Within two hours, the problem is solved and your shelves no longer trigger thoughts of food insecurity. Amazon gets the business, the delivery fees, and the data. Costco be damned. I can’t be the only person who routinely does this.

The market for this consumer behavior is due to grow. Amazon Prime, which typically comes with a $139 annual fee, has a cheaper option for those in need and you’re going to hear more about it. Prime Access, while available since 2017, was recently pushed by Amazon (Amazon expanded upon this program in October 2022). Likely as a solution for a two-pronged problem:

  • remaining inflationary effects (4.9%)
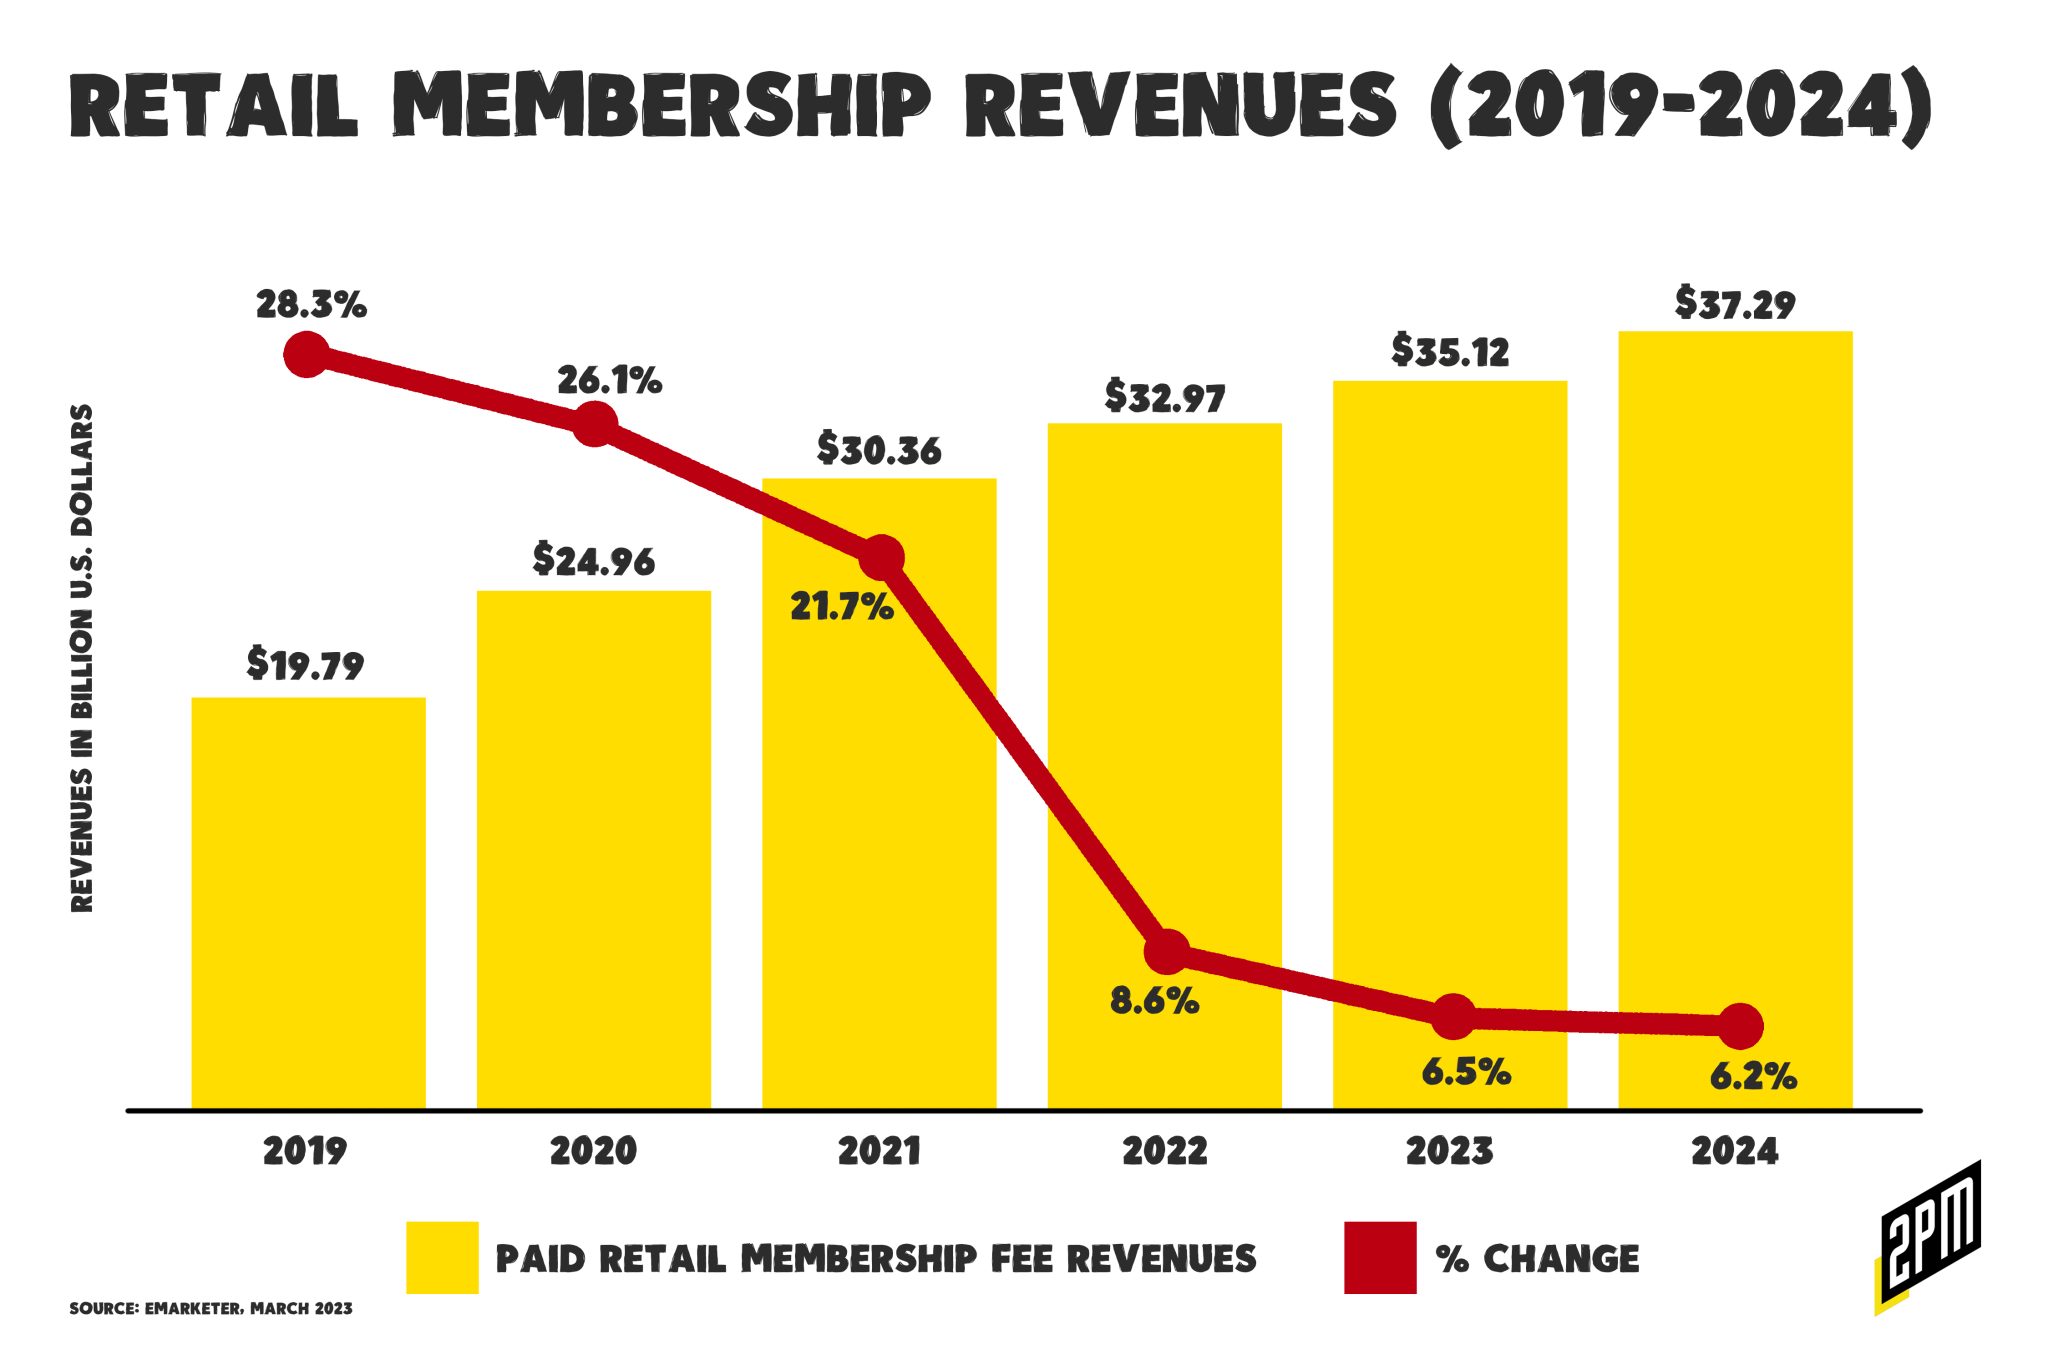
  • the fall in retail membership revenues

Soon enough, the app may reflect grocery options that may be more economical. More on that in a moment.

Amazon has often been at the forefront of eCommerce evolution, from its origin as a digital bookstore to its current status as a colossal multi-industry conglomerate. Its April 2023 evangelism of Prime Access (a six year old program) and one designed to democratize Amazon Prime for lower-income users, is another testament to the company’s need to adjust to retail’s evolution.

Prime Access is Amazon’s discounted membership program for qualifying government programs. Eligible customers in the U.S. who sign up receive all of the privileges of Amazon Prime at around 50% off of the typical membership.

Prime Access could significantly impact Amazon’s potential growth against the backdrop of declining industry-wide membership revenue growth. According to membership startup Inveterate who powers the following companies’ membership loyalty programs: Liquid IV, Fresh Clean Tees, Lashify, Fly by Jing, Flamingo Estate, and a number of others:

A study by Deloitte found that 67% of consumers would join a paid loyalty program if it offered significant benefits (compared to just 33% who said the same for free points-based programs).

Amazon is hoping to capture, or even improve, the remaining growth by appealing to a larger audience who may be interested in paid loyalty programs. As it stands, Amazon Prime remains the highest-rated loyalty program according to an October 2022 survey by Activate. This includes CostCo, Sam’s Club, Walmart+, and Instacart+. But growth has predictably slowed.

Traditionally, Amazon Prime has been perceived as a luxury-adjacent good, predominantly catering to higher-income households. However, this new initiative represents a significant expansion of Amazon’s target market. By leveraging a range of government programs, Amazon is making its premium services accessible to a broader demographic, thereby widening its potential user base and revenue streams. This move demonstrates the power of membership-driven, app-based eCommerce: by lowering the barrier to entry, Amazon can tap into a lesser-served (but growing) market, boosting its growth potential. This could be the antidote.

The power of simplicity in commerce, especially in the context of one-click, repeat purchases in app-based marketplaces like Amazon Prime, cannot be overstated (here is a recent deep dive on that topic). The Amazon model has excelled by offering a seamless, frictionless shopping experience. The fewer the steps a consumer has to take to complete a purchase, the higher the likelihood of conversion. By making the purchasing process as simple as possible, Amazon encourages users to make repeat purchases, fostering customer loyalty and driving sales. In the context of democratizing commerce, I believe that there is a cause for concern.

In line with the principle of simplicity, Prime Access also serves to democratize eCommerce. According to Amazon, you can provide proof of eligibility or participation from the following programs:

  • SNAP EBT
  • Medicaid
  • Woman, Infants, and Children Program (WIC)
  • Supplemental Security Income (SSI)
  • Direct Express Debit Card (DE)
  • Temporary Assistance for Needy Families (TANF)
  • National School Lunch Program (NSLP)
  • Low Income Home Energy Assistance Program (LIHEAP)
  • Tribal Assistance Eligibility Letter (TTANF)
  • Nutrition Assistance Program (NAP)

Traditionally, online shopping has been skewed towards those with higher disposable incomes and access to credit cards. By allowing access to Prime benefits through participation in various government assistance programs, Amazon is broadening the scope of the online retail market. This move democratizes the market for commerce by offering the same conveniences and advantages of online shopping to a demographic that has only recently become the focus of enterprise retailers:

Consider it the new direct-to-consumer retail. Shipping orders directly from their origin factories keeps prices low. Shein, the Chinese ultra-fast-fashion giant, has taken the world by storm and continues to grow in magnitude, dwarfing the SKU counts and volume of sales of competitors like Zara, H&M and Boohoo. The clothes are cheap, disposable, and addicting. Temu could fulfill a similar desire for “cheap yet good-enough” products – especially as America’s historic run of inflation continues to tilt consumer prices upward.

Chinese-owned, cross-border commerce companies like Shein and Temu are laser-focused on this demographic but few can reach them like Amazon. It’s the ease of purchase, the product availability, the pricing transparency, and the proximity to consumer. Relevant to this conversation, there’s rumor that Amazon may acquire 500 locations that Albertsons and Kroger plan to divest. These stores would enable Amazon to grow its Amazon Fresh option, a more economical source of goods than what’s commonly found at Whole Foods. In short, Whole Foods can only scale so much.

In a letter to shareholders in early April, Amazon CEO Andy Jassy said the grocery business, which has struggled to get off the ground, needs to be a focal point of the company’s strategy. Back in 2017 Amazon paid $13.7 billion for the Whole Foods chain, but that has come with bumps and bruises. Amazon also has been forced to close Amazon Go and Amazon Fresh locations, and has laid off thousands of workers. Amazon announced in February it was pausing the rollout of its Amazon Fresh stores while it re-evaluated the concept’s economics.

The awareness of this program and the further democratization to follow is not without its potential downsides. One such concern lies in the implications of Amazon enabling impulse purchases, during periods of great economic uncertainty, for essentials such as groceries and in-home needs with a credit card. With the convenience of one-click purchases and the temptation of a vast array of products, consumers may find themselves spending beyond their means, which could lead to increased levels of debt.

While this is a potential risk, it’s important to note that the convenience of online shopping, particularly for essentials, can also serve as a financial planning tool. For example, the ability to compare prices and products can help shoppers make more informed decisions, potentially saving money in the long run. Additionally, the convenience of home delivery can save on transportation costs, especially for those living in food deserts or areas with limited access to stores.

Amazon’s evangelism of Prime Access underscores the transformative power of membership-driven, app-based eCommerce in grocery and household goods. By advertising democratized access to its Prime services, Amazon is not only expanding its potential growth but also paving the way for more inclusive commerce. At the same time, this development highlights the need for consumer education to mitigate the potential for increased debt. As the eCommerce market continues to evolve, it’s crucial that advancements in convenience and accessibility are balanced with measures to promote responsible spending.

By Web Smith | Edited by Hilary Milnes with art by Alex Remy and Christina Williams

Member Brief: Data that Rings Alarm

Temporarily unlocked. There are no answers here, few forecasts and no real predictions. This is just a reaction to surprising data. Behind closed doors at retailers everywhere, large and small, I suspect that this is the conversation being had.

That outlet mall was 11 minutes away from the home where I spent my elementary school years. A lot has changed in that part of Texas since the early 1990s. Allen, Texas wasn’t the nationally ranked wealth suburb back then. Today, the median household income is $113,719. Unemployment is 4.3% and poverty is negligible. It’s an idyllic place. It’s the idea of the suburb that I wrote about when I explained my concept of Sanitized Urbanization. Few states build suburbs better than Texas. In short, “sanitized urbanization takes the best parts of urban renewal and imports them to upper-middle class and wealthy exurbs.” It was a quote by Noah Smith, a Bloomberg columnist, that spurred this idea along:

“The suburbs” won’t mean exactly what it meant in the 1970s. Then, the term conjured visions of malls, single-family houses separated by broad lawns, and homogeneous White populations. In order to attract today’s urbanites, suburbs will have to offer something a bit different. [Crain’s]

I went on to explain how most metropolitan areas like Dallas are adopting a format that allows for each suburban area to be self-sustaining with its own retail centers, medical facilities, and living spaces. Polycentric development (having more than one center) is a pattern of transport connectivity, urban planning, mixed use development, and progressive city  design. The result of this type of development is a classification of suburban development that has become more commonplace as younger earners continue to flee cities.

Join – Yearly Membership

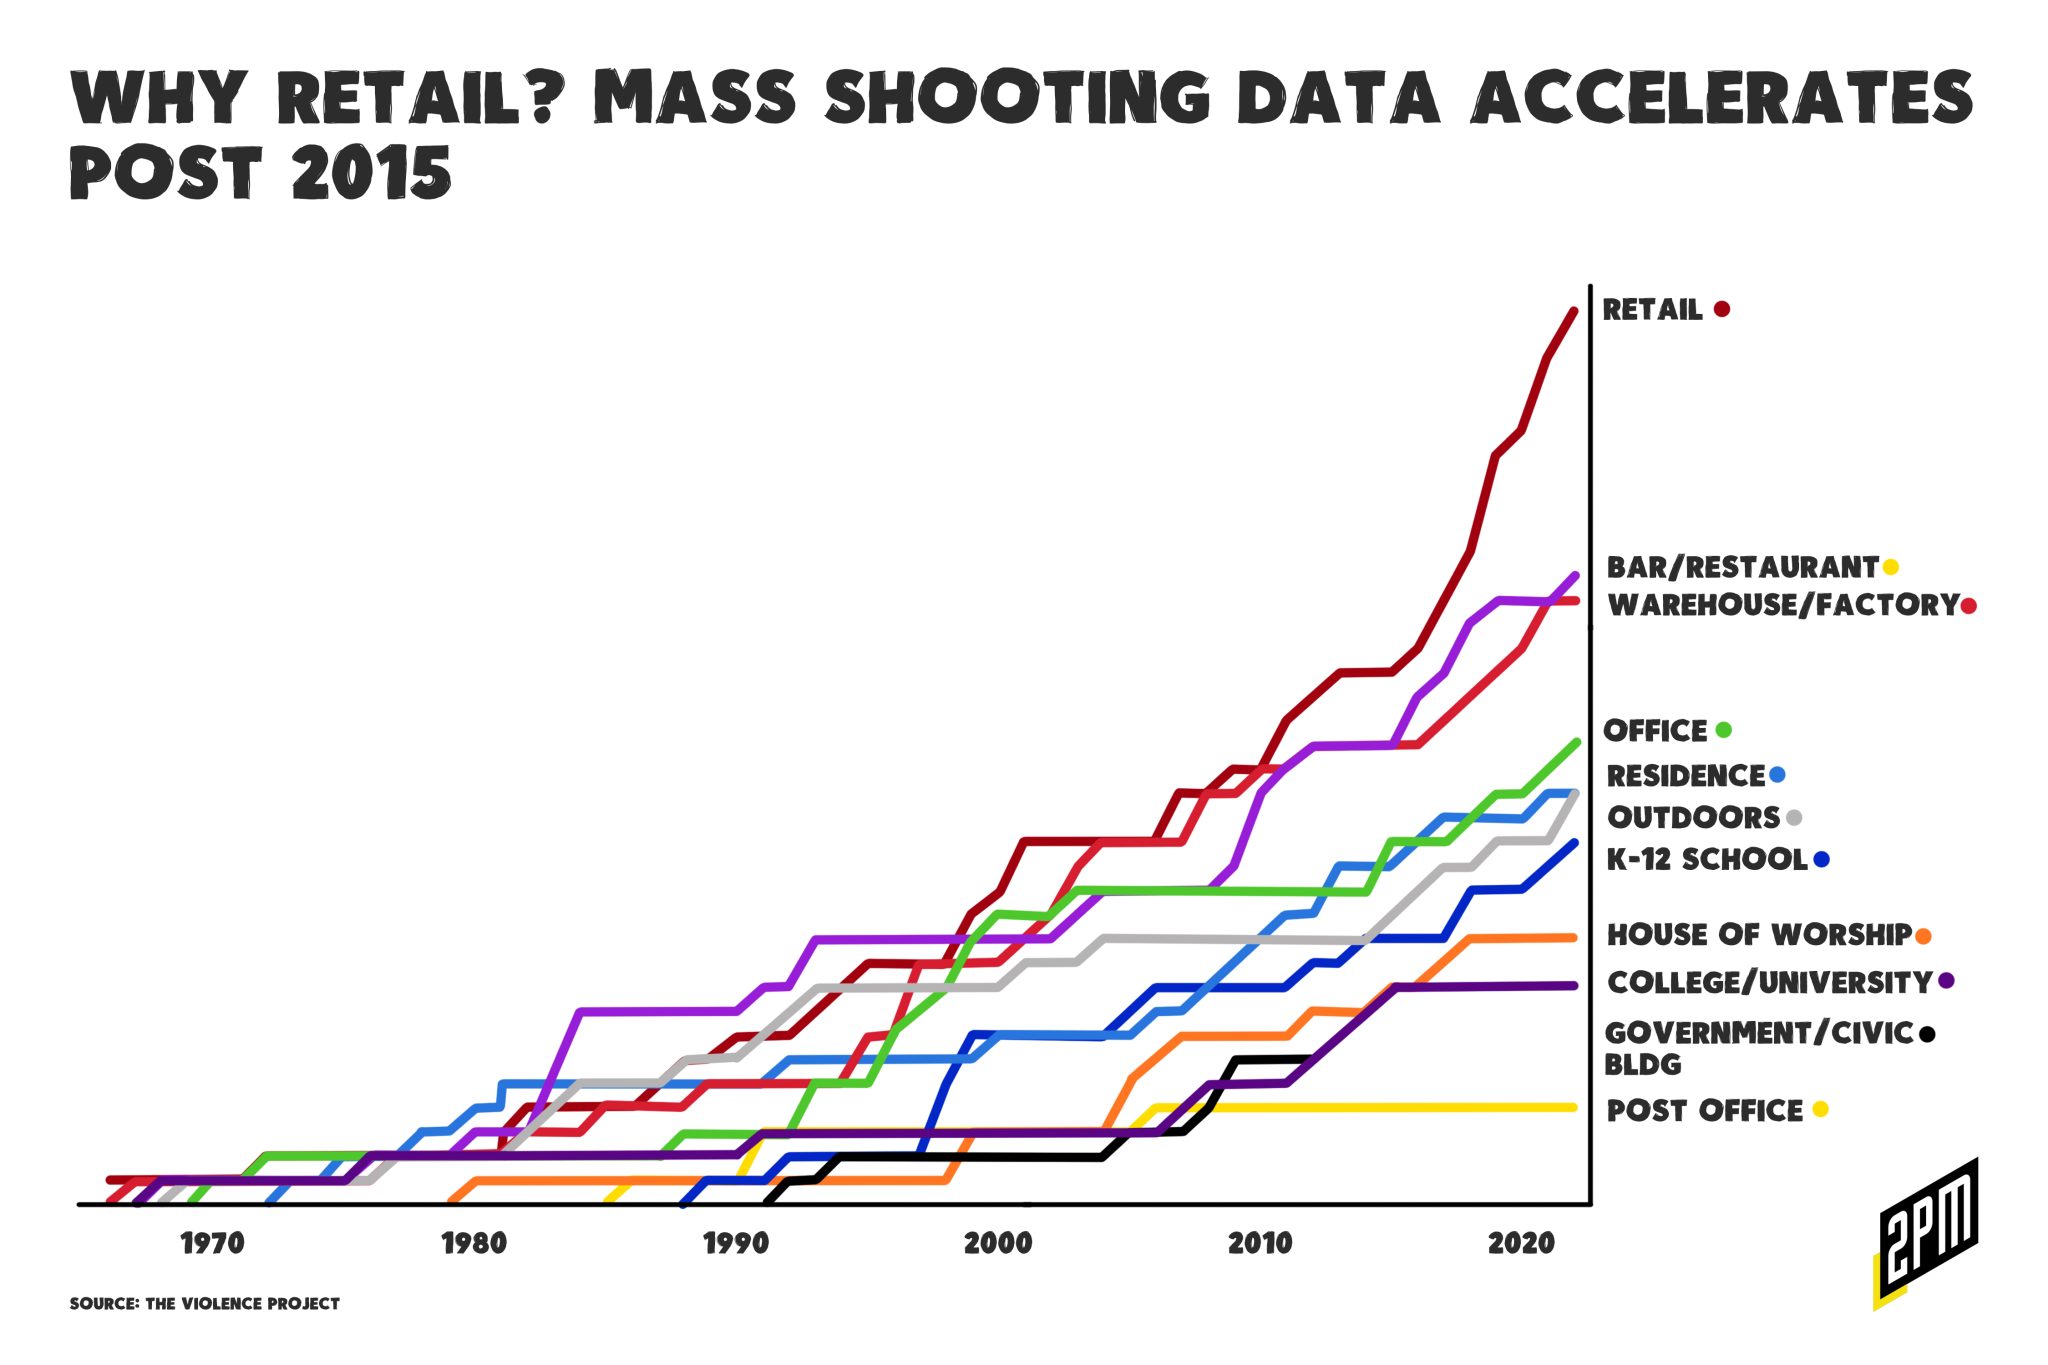
It’s against this backdrop that I view the tragic loss of life in an area that has never experienced this magnitude of violence. New data from the Violence Project suggests that the type of violence that occurred in Allen, Texas is accelerating.

We often think of schools as the primary targets of these acts of needless violence, but while every act is, in itself, awful: retail is now at the center of it.

Until recently, the average American who viewed cable news categorized retail crime as acts of theft and vandalism concentrated in areas like San Francisco, Los Angeles, New York City, Oakland, Miami, and Chicago. In the 2022 National Retail Federation’s Retail Security Survey, the most pressing issues as it related to the “risk and threat priorities” of retail executives were guest-on-associate violence, external theft, organized retail crime and cyber crimes. “Mass violence” was in the fifth position with 28.1% of executives suggesting that it was “somewhat more” concerning and 29.8% of those polled believing that it was much more concerning. This priority list my change in the coming months.

As retail executives, it is crucial to understand the evolving landscape of public safety and its impact on brick and mortar businesses. The recent tragic mass shooting at the Premium Outlet in Allen, Texas has highlighted the vulnerability of retail locations to such acts of violence. While it is a retail problem, the real solution is not in the control of the retail industry itself. The narrative will need to elevate the concerns around the social contagion that is the targeting of innocent civilians in retail locations and nearby restaurants. I found this paragraph from a recent journal article in the National Library of Medicine to be relevant to one explanation of the data mentioned in this report.

Recently a contagion effect, similar to a “copycat” effect, has been suggested in mass shootings. This effect suggests that behaviors can be “contagious” and spread across a population. In the example of mass shootings, a contagion effect would be said to exist if a single mass shooting incident increased the likelihood of other instances of mass shootings in the near future. Contagion has been documented across a variety of other behaviors, including airplane hijackings, smoking cessation, and binge eating, and has been well researched in relation to suicide. There is now evidence that when a mass shooting occurs, there is a temporary increase in the probability of another event within the next 13 days on average.

So I found it valuable to explore the history of retail shootings from 1969 to 2022 as well as any and all implications for brick and mortar businesses in the coming years. This includes the likelihood of increased visibility of armed guards at malls, potential militarization of on-site police officers, and the potential shift towards online retail due to changing attitudes towards safety.

A Historical Perspective: 1969-2022

1969-1990: During this period, mass shootings in retail spaces were relatively uncommon. Although incidents like the 1980 shooting at the Liberty City Shopping Center in Miami, Florida, which claimed two lives, raised concerns, there was limited public awareness about the potential risks associated with retail locations. Consequently, security measures were not significantly heightened during this time.

1990-2000: The 1990s witnessed an increase in retail shootings, bringing the issue to the forefront. The tragic 1992 shooting at the Fort Hood Mall in Killeen, Texas, where 23 lives were lost, was a turning point. This incident sparked discussions about the necessity of enhancing safety protocols in malls. While some malls began implementing security measures such as increased surveillance and limited access points, the overall response remained relatively limited.

2000-2010: Mass shootings in retail locations continued to occur with alarming frequency during this period. Incidents such as the 2007 Trolley Square shooting in Salt Lake City, Utah, and the 2008 Westroads Mall shooting in Omaha, Nebraska, further underscored the urgent need for improved security. These incidents prompted retailers to collaborate more closely with law enforcement agencies to enhance security measures. However, the scale of the problem remained significant.

2010-2022: Mass shootings at retail locations reached a distressing peak during this period. Incidents such as the 2012 Aurora theater shooting in Colorado and the 2019 Walmart shooting in El Paso, Texas, where numerous lives were lost, amplified public concerns about safety in retail spaces. Retailers began taking security more seriously and worked to improve measures to protect their customers and employees. However, the high number of incidents continued to pose challenges.

Here is a breakdown of the alarming data surrounding mass shootings, detailed by year (source: The Violence Project):

YEARK-12CollegeGov BuildingChurchRetailDiningOfficeResidenceOutdoorsWarehousePost Office
196601001000000
196701001000010
196801001100010
196901001100110
197001001110110
197101001110110
197201002120110
197301002121110
197401002121110
197501002122110
197602002122110
197702002222220
197802002322220
197902002322220
198002012423220
198102012423220
198102013523220
198202014523330
198302014525430
198402014825530
198502014825540
198602014825541
198702015825541
198802016835641
198912016835651
199012017835651
199113017935753
199223117936853
1993231181156953
1994232191156953
19952321101156973
19962321101176973
199723211011869103
199853211011969103
1999732312111169103
2000732313111279103
20017323151112710113
20027323151112710123
20037323151213710143
20047323151313711153
20058335151313711153
20069336151313811154
20079437171313811154
20089547171313911174
200995671814131011174
201095671817131111184
201195672018131211184
2012106682119131211194
2013107782219131411194
2014118882219131411194
2015119992219151412194
2016119992321151513194
20171199102522151614204
20181399112724161614214
20191399113125171615224
20201399113225171615234
20211499113525181715254
20221599113726191717254

Growing up, it was a widely held belief that the most dangerous schools were the ones with metal detectors. These were the schools in rougher parts of town; violence was anticipated and so was the presence of law enforcement. Even today, the best public high schools in the United States avoid this measure. They believe that it would communicate that the assumption of safety was a lost cause. While this is the prevailing behavior in K-12 schools, retail centers may not hold similar beliefs.

Projected Impact and Market Assumptions

Increased visibility of armed guards: In the wake of the rising frequency of retail shootings, it is likely that malls and retail locations will prioritize security measures to ensure the safety of shoppers. Armed guards may become more visible, acting as a deterrent and providing rapid response in case of emergencies. This heightened security presence will aim to instill a sense of safety among shoppers and employees, encouraging them to continue visiting physical stores. The presence of armed guards can also serve as a proactive measure, potentially deterring potential assailants.

Potential militarization of police officers: Given the gravity of the trend line, it is possible that police officers responding to retail shootings will appear more militarized. The aim would be to swiftly neutralize threats and minimize casualties. However, striking a balance between effective response and maintaining a welcoming environment is crucial to prevent unnecessary fear or discomfort for shoppers. Collaboration between law enforcement agencies and retailers will play a vital role in establishing guidelines that prioritize both safety and the customer experience.

Shift towards online retail: The changing attitudes towards safety in retail spaces may inadvertently lead to a shift towards online retail. Consumers, increasingly concerned about their wellbeing, may opt for the convenience and perceived safety of online shopping. This shift poses challenges for traditional brick-and-mortar retailers. To adapt, retailers must invest in developing robust online platforms and implementing effective omnichannel strategies that seamlessly integrate their online and offline presence. This approach allows retailers to cater to changing consumer preferences while providing a consistent brand experience.

Retailers may likely leverage the shift towards online retail by enhancing their digital marketing efforts, improving website user experience, and offering personalized recommendations to engage customers. The Connected Mall concept that I wrote about in 2020 will become commonplace throughout the many, premium suburban malls peppering the United States.

Here is that thesis. Easton Town Center, the premium retailer at the center of the thesis eventually facilitated the operation (same day shipping in a 20 mile radius), though the solution still appears early.

It is important to note that the shift towards online retail is not a complete solution. The risk of violence should not keep customers out of stores. Many consumers still value the tangible experience of visiting physical stores, socializing, and engaging with products firsthand. Therefore, brick and mortar retailers should focus on creating unique in-store experiences that emphasize safety while recognizing that there’s only so much that can be done without governmental intervention.

Looking ahead to 2025, the market assumptions for brick and mortar businesses are multifaceted. On one hand, the demand for enhanced safety measures and visible security presence may lead to increased costs for retailers. Budget allocations for security personnel, technology upgrades, and training programs may rise to ensure the safety and well-being of customers and employees. Retailers should view these investments as vital for building trust, maintaining a secure environment, and mitigating potential risks.

On the other hand, the integration of advanced technologies like artificial intelligence (AI), machine learning (ML), and data analytics can help retailers optimize their security strategies. AI-powered surveillance systems can identify potential threats in real-time and trigger immediate alerts, enabling a proactive response. ML algorithms can analyze historical data to identify patterns and predict potential risks, assisting retailers in implementing safety measures. I anticipate these types of preventative measures to become more common.

The history of retail shootings at malls reflects an unfortunate reality of our society. It is crucial to acknowledge the impact of such incidents and proactively address safety concerns to ensure the longevity and success of brick and mortar businesses. By increasing the visibility of armed guards, collaborating with law enforcement agencies, and embracing technology for both online and in-store experiences, retailers can navigate the evolving landscape of safety, build consumer trust, and maintain a competitive edge in the retail industry.

Without viewing retail violence with a proactive lens, the concept of the suburban mall, one of the enduring tentpoles in American capitalism will be unrecognizable. And given that this sort of violence is less tolerable to many (than the same magnitude of violence elsewhere), the irony is not lost on me. Capitalism is at stake and retail is America’s chief employer. Maybe then, something will have to be done about it – in a way that respects personal liberty while also respecting the importance of life.

Retail has been at the center of a political maelstrom for a while now but the Allen, Texas massacre is likely to exacerbate things. Adapting to this, the changing consumer attitudes, fears and preferences will be vital in fostering a secure shopping environment. Ultimately, the answers to these concerns will determine the future of retail in the United States.

By Web Smith | Edited by Hilary Milnes with art by Alex Remy and Christina Williams

Part one of this series: Where NatSec Meets Commerce (China’s Influence)

Editor’s Note: I hate the phrase “thoughts and prayers” because it denotes a powerlessness to affect change. My hope is that the contribution of this perspective helps in some way, shape or form. My sincerest condolences to the families, businesses, and lost lives impacted by this tragic event.