Deep Dive: Cutthroat Grocery and The Replenishment Economy

To better understand the increasingly cutthroat grocery industry, I read “The Secret Life of Groceries” by Benjamin Lorr, elements of which will be summarized here. It opened my eyes to say the least; I will never consume another package of beef, seafood, berries, packaged salad snacks, or even my favorite canned drink without thinking about the sacrifice required to get those products to our doors.

The secret to successful grocery shopping lies in understanding the psychology behind product placement and marketing. […] In the modern grocery industry, competition is fierce, with retailers constantly vying for our attention and loyalty.

The modern grocery store is a marvel of contemporary commerce, revolutionizing the way we shop, eat, and live. It’s also as cutthroat as the industries that we have historically associated with that descriptor: oil and gas, textiles, and any others that we know to have elements of violence, forced labor, or worse.

Let’s first begin with some history.

****

The evolution of the grocery store began with the introduction of Piggly Wiggly in Memphis, Tennessee, in 1916 by Clarence Saunders. This was the first self-service grocery store, revolutionizing the retail landscape by allowing customers to browse and select their own products, a departure from the traditional clerk-assisted model.

In 1937, Sylvan Goldman, an Oklahoma businessman, further transformed the shopping experience with the invention of the shopping cart. Observing that shoppers stopped purchasing when their baskets became too heavy, Goldman created a wheeled cart with baskets, increasing convenience and encouraging more purchases.

The grocery industry continued to innovate with the establishment of larger chains. Kroger, founded in 1883, grew into a major player by implementing many of the modern retail practices developed by Piggly Wiggly and Mr. Goldman, expanding its range of products and services. Whole Foods, launched in 1980, targeted health-conscious consumers with its focus on organic and natural foods, and in 2017, it was acquired by Amazon for $13.7 billion.

Trader Joe’s, founded in 1967, distinguished itself with unique private label products (effectively launching the private label industry) and a quirky, customer-centric approach. Aldi, which entered the U.S. market in 1976, offered a no-frills, cost-effective shopping experience that appealed to budget-conscious shoppers.

These pioneers laid the foundation for today’s diverse and competitive grocery landscape, characterized by innovation, convenience, and a constant evolution to meet changing consumer demands.

****

According to the Bureau of Labor Statistics: in 1901, Americans had an average spend of 42.5% of the household budgets on groceries. By the 1930s, that number was around 33% and today: American consumers spend just 11% of their household income on groceries. Until recently at least (buoyed by a higher CPI and persisting inflation), food felt available and commoditized. Lorr’s book made me realize just how much of a false perception that is.

Far from being simple retailers of food, grocery stores have evolved into complex entities that reflect broader social, economic, and technological trends. From the humble beginnings of self-service stores in the early 20th century to the sprawling supermarkets and specialized grocers of today, the grocery industry has become a fiercely competitive and dynamic segment of retail. This report will explore the rise of the grocer, the intricacies of supply chains, the cutthroat nature of the industry, and the intensifying challenges faced by CPG brands in an evolving retail landscape.

Yesterday And Today: A Lesson To Modern Retail

Trader Joe’s, a beloved grocery chain known for its unique products and customer-centric approach, owes its success to the visionary leadership of its founder, Joe Coulombe. After graduating from Stanford in 1958, Coulombe initially worked for Rexall, the largest retail pharmacy chain at the time, where he successfully developed a new line of convenience stores called Pronto Markets. When Rexall decided to shut these stores down, Coulombe borrowed money, bought them himself, and transitioned from a corporate employee to a determined entrepreneur.

Recognizing the impending competition from 7-Eleven, Coulombe pivoted his business model. He rebranded his stores with a South Seas motif, diversified the product range, and named the new venture Trader Joe’s. His ability to foresee and capitalize on emerging trends was a key factor in his success. With Boeing’s introduction of the 747, Coulombe anticipated that increased international travel would spark American consumers’ interest in exotic foods. This led him to stock Trader Joe’s with unique, imported foods that stood out from the typical American grocery offerings.

Coulombe also had a keen understanding of his target market. He identified “overeducated and underpaid” individuals—screenwriters, musicians, museum curators, and journalists—as his core customers. This focus on a specific demographic allowed him to tailor the product offerings to their tastes and preferences. Trader Joe’s became known for its eclectic mix of products, including private label items that bolstered profits, such as the now-iconic almond butter.

Another innovative strategy was the localization of stores. Unlike other chains with identical store layouts, Trader Joe’s stores featured unique decorations and murals created by in-house artists to reflect the local community. This approach fostered a sense of connection between the store and its neighborhood, enhancing customer loyalty.

Listening to customers was also a cornerstone of Trader Joe’s success. Coulombe consistently responded to customer feedback by adding more organic and healthy items, eliminating products sourced from China due to safety concerns, and phasing out plastic packaging. This responsiveness helped maintain customer trust and loyalty over the years.

A significant differentiator for Trader Joe’s was its wine section. Coulombe, a wine enthusiast, recognized that educated consumers tended to drink more wine. By dedicating a substantial portion of store space to value wines, particularly from California, Trader Joe’s attracted wine lovers who then discovered the store’s unique food offerings. The introduction of “Two Buck Chuck,” a private label wine sold for $1.99, became a cultural phenomenon and drew countless new customers to Trader Joe’s.

Today, despite being owned by a German company, Trader Joe’s continues to operate on the principles established by Joe Coulombe. Yes, Trader Joes’s is owned by the same family that owns Aldi’s.

Trader Joe’s founder Joe Coulombe sold his business to Theo Albrecht in 1979, officially making the Albrecht family the proud owners of both prosperous markets — specifically, the Aldi Nord branch, since the company is split into two.

His early vision was remarkably prescient, anticipating many trends that define the modern grocery industry: a focus on imports, catering to educated consumers, creating new products from existing commodities, and leveraging private labeling to enhance profitability. Trader Joe’s success story is a testament to entrepreneurial foresight, customer focus, and innovative thinking.

Before the rise of supermarkets, grocery shopping involved visiting multiple specialized shops—bakeries, butcheries, and green grocers—which was time-consuming and often inconvenient. The supermarket consolidated these various food categories under one roof, offering remarkable convenience and unprecedented variety. This evolution continued post-World War II, driven by suburbanization and the growth of the middle class, resulting in the architectural behemoths we recognize today. These behemoths come with plastic baggage.

Complexities of the Supply Chain

The seamless operation of a modern grocery store depends on an intricate and often unseen network of supply chains that span the globe. These supply chains involve numerous players, including farmers, manufacturers, distributors, and retailers, all working in concert to meet consumer demand. However, behind the scenes lies a world fraught with challenges, some of which reveal troubling ethical issues.

Notice the reduction in export volume after reports of exploitation near Thailand’s shrimping business’ peak.

One of the most harrowing aspects of the global food supply chain is the exploitation of labor, exemplified by the Thai shrimp industry. Lorr’s book revealed harrowing stories that span from backroom workers in your favorite Whole Foods to the economic and physical dangers of trucking, to the aforementioned Thai shrimp industry’s literal slavery. I don’t use that term as a figure of speech.

His investigations uncovered severe abuses, including forced labor and human trafficking, where workers are subjected to brutal conditions and treated as modern-day slaves at worst or indentured servants at best. These practices are driven by the relentless demand for cheap seafood in Western markets, highlighting a dark side of globalization and the hidden human cost embedded in our groceries.

The complexity of the supply chain also involves logistical challenges. Maintaining the freshness and quality of perishable goods requires sophisticated refrigeration systems and efficient transportation routes. Just-in-time inventory systems, designed to reduce storage costs and inventory holding times, demand flawless synchronization. And the global dimension of the supply chain introduces regulatory, political, and environmental hurdles that must be navigated carefully.

Geopolitics and the Future of Grocery Retail

The future of the grocery industry will increasingly rely on executives who are aware of these intensifying concerns. The global nature of food supply chains means that political instability, trade disputes, and regulatory changes can have profound impacts on the availability and cost of products. Executives must learn to navigate these challenges while balancing the demands for ethical sourcing, sustainability, and profitability.

Amazon’s Subscribe & Save, has shifted consumer behavior, reducing in-store shopping for non-perishable items. Technological advancements will play a crucial role in shaping the future of grocery retail. The rise of eCommerce and online grocery shopping has transformed consumer habits. In Subscription Box Fatigue, I wrote about what is now called “replenishment shopping”:

This direction is more than a business expansion; it’s a strategic alignment with the changing behaviors of consumers who crave simplicity and convenience in their shopping experience. By securing a spot in the inventory of stores affiliated with Amazon Prime or Instacart, DTC brands can ensure their products are as accessible as a click or a quick grocery run. They can also build an insurance model for the growing subscription fatigue that seems to be triggered by rising economic concerns.

Replenishment shopping, or the frequent one-click acquisition of goods to replace diminished inventory, for non-perishables has significantly altered the grocery shopping experience for retailers, consumers, and store brands. Rather than strict subscription purchases, customers have a loose automation by way of platforms like Amazon, Instacart, DoorDash, or UberEats. Retailers like Walmart are losing market share of center-aisle products—such as paper towels, toilet paper, consumer packaged goods and canned goods—to eCommerce subscription services like Amazon’s Subscribe & Save. This shift means that consumers are spending less time in physical stores, with 42% of retail subscribers shopping in-store less often due to their subscriptions.

PYMNTS Senior Vice President and Head of Analytics Scott Murray noted: Paper towels, toilet paper and even cans of soup and things like that, but when it comes to perishables, I think people generally still go [to stores].

For traditional grocery retailers (with exception of Trader Joe’s and Aldi’s apparently), this poses a threat, necessitating a shift towards convenience-oriented channels such as same-day delivery to retain customer loyalty. Consumers benefit from the convenience and cost savings of subscription services, while store brands must innovate to compete with these new purchasing patterns. Overall, the rise of replenishment shopping is reshaping the grocery landscape, emphasizing the need for retailers to adapt to evolving consumer behaviors and preferences.

Changing Dynamics Between Retailers and CPG

This disruption and innovation have significantly altered the relationship between retailers and CPG companies. Both have invested heavily in new technology, channels, product development, and consumer touchpoints to stay relevant. However, their evolving roles and strategies have created tension as each takes on parts of the other’s traditional functions and innovates in different ways.

The American consumer is eating less beef but far more expensive beef, benefiting retailers.

Retailers, especially in the grocery sector, have become more empowered. The pandemic accelerated technology plans, leading to the implementation of contactless payments, self-service checkouts, click-and-collect services, and expanded delivery options. Retailers have also extended their private label product ranges and improved the customer experience, driving convenience, efficiency, and value; CPG brands lose when this strategy succeeds. In some cases, grocers have positioned themselves as defenders of the consumer, pushing back against excessive price increases from CPG companies and refusing to stock certain branded goods.

Conversely, CPG companies have sought to reduce their distance from consumers by developing replenishment business models, including websites, loose subscription models, and advertising partnerships on platforms like Instacart that can remind the customer that product availability is theirs for the taking. The best performing ones have focused on making supply chains more flexible and responsive, reviewing ingredients and recipes to reduce costs and be more sustainable, and exploring various physical channels beyond major grocery stores.

Additional Challenges for CPG Brands

The shifting dynamics have made the grocery industry particularly challenging. Shelf space is at a premium, with retailers exercising greater control over their product offerings. The EY Future Consumer Index indicates that consumers are turning away from once-favored brands, with many opting for private label products. Branded products now come in smaller pack sizes, and consumers are more willing to switch to new products if they offer better quality or value.

As more consumers turn to online shopping for the bulk of their replenishment shopping, traditional grocery stores face challenges in maintaining their margins and adapting to a fragmented shopping environment.

CPG companies are finding it increasingly difficult to control their product narrative in a landscape where information is readily available, and consumers are more informed than ever. Transparency, authenticity, and purpose have become crucial in maintaining consumer trust and loyalty. However, with limited opportunities to communicate these attributes at the point of sale, CPG brands must invest in multiple channels to maintain visibility and control their brand message. This, of course, can be incredibly costly at a time when consumers feel economically disadvantaged as a whole.

Consumers are increasingly looking for ways to control their spending amid financial challenges. Recent PYMNTS Intelligence data shows that a significant percentage of consumers have altered their grocery shopping habits due to rising prices, cutting down on nonessential spending and switching to cheaper merchants. This shift underscores the need for both retailers and CPG companies to adapt to the changing economic landscape and consumer behavior.

****

The rise of the grocer, from the early days of self-service stores to the sophisticated supermarkets of today, reflects broader trends in consumer behavior, technology, and globalization. The complexities of supply chains, including troubling ethical issues like forced labor, highlight the hidden costs behind our groceries. The grocery industry remains one of the most cutthroat segments in retail, requiring constant innovation and adaptation.

As the industry moves forward, it will increasingly depend on executives who are attuned to geopolitical concerns and capable of navigating a complex global landscape. The future of grocery shopping will be shaped by technological advancements and a continued focus on ethical and sustainable practices.

As consumers become more conscious, expect aggregate volume of meat consumed to continue falling.

In an ecosystem as interdependent as this one, success now is about fostering open, collaborative, and agile ways of thinking and working. Retailers and CPG companies must leverage each other’s strengths and innovations to approach the future from a position of strength. Ultimately, it’s critical to continue understanding the consumer.

The changes in the way CPG and retail work together could present an opportunity for a more radical rethink, not just of how they go to market, but how they measure success in a continually changing world. As the grocery industry navigates these challenges, it will remain a vital and dynamic part of our daily lives. This final quote by Benjamin Lorr is one that I am unlikely to forget.

To narrow down their efforts, [Humanity United] focused on industries that were likely to achieve a media hit: Was the product imported into the United States in significant quantities? Would the severity of abuse shock consumers? Ten different commodities met these new criteria: chocolate, coffee, shrimp, cattle, conflict minerals such as tungsten, cotton, timber, sugar, palm oil, and gold.

History has proven that when you do the right thing for the consumer, the entire consumer ecosystem wins. But if I have learned anything throughout this research, it’s that consumer wins often mean labor – at some point in the supply chain – is suffering a cutthroat loss. Six of the commodities that Humanity United pinpointed are ones that make our grocery industry go.

I believe that this is the most important thing to remember when shopping for what we all seem to take for granted: groceries. It’s a system that allows us to “hate our shrimp but eat it too,” as Lorr so eloquently put it. As the replenishment economy continues to grow, we will only be farther removed from the supply chains that do the work to make same day grocery delivery possible.

Research, Writing, and Data by Web Smith 

Deep Dive: Shipping Matters

In 2024: Three Issues That Will Define Commerce, I highlighted a critical intersection where three major influences: cybersecurity, shipping vulnerabilities, and geopolitical concerns —were poised to impact the global retail landscape. The analysis ended, “The flow of commerce faces further disruption.” This essay delves into what that could look like and why.

Let’s fast forward to mid-2024, these predictions have not only materialized but have also evolved, presenting an even more complex challenge for global commerce. This update revisits those projections in light of new data and insights.

In my December 2023 analysis, I covered the emerging intersection of national security and commerce, specifically in light of shipping concerns. The geopolitical tensions in the Suez Canal Zone were converging to create a multifaceted challenge for retailers. This convergence underscored the need for a strategic approach to safeguarding both national and corporate interests while maintaining a thriving global economy.

****

A History: The Suez Canal Zone

The Suez Canal Zone held significant military importance between 1945 and 1956, serving as a strategic and economically vital route for Middle Eastern oil and trade with the Far East. British forces were garrisoned in the Canal Zone under the terms of a 1936 treaty to protect this crucial passage. Despite its strategic value, the posting was unpopular among soldiers due to the harsh climate, frequent diseases, and hostility from Egyptian nationalists.

British presence in the Suez Canal Zone was essential for maintaining control over the key maritime route that connected the Mediterranean Sea to the Indian Ocean, facilitating faster trade between Europe and Asia. However, Egyptian resentment towards British occupation led to increasing violence and unrest, particularly between 1950 and 1956. This period saw numerous attacks on British soldiers, escalating tensions, and significant casualties on both sides. The culmination of these tensions came with the disarming of the police in Ismailia in January 1952, leading to further violence and British casualties.

Negotiations led by Colonel Gamal Abdel Nasser resulted in the 1954 agreement to end the British occupation. By 1956, British troops had fully withdrawn from the Canal Zone, marking the end of an era of direct British military presence in Egypt. Despite the challenges faced, the military importance of the Suez Canal Zone during this period underscored its pivotal role in global trade and geopolitical strategy.

Today, the Suez Canal remains a critical artery for global commerce, but its management has shifted significantly. The Suez Canal Authority (SCA), an Egyptian state-owned entity, now oversees the canal’s operations. The SCA is responsible for maintaining and expanding the canal to accommodate modern shipping demands. The canal has undergone several expansions, most notably the Suez Canal Expansion Project completed in 2015, which aimed to increase the canal’s capacity and reduce waiting times for vessels. In December 2023, the U.S. Secretary of Defense Lloyd Austin announced a 10 country coalition to better protect the Suez route.

****

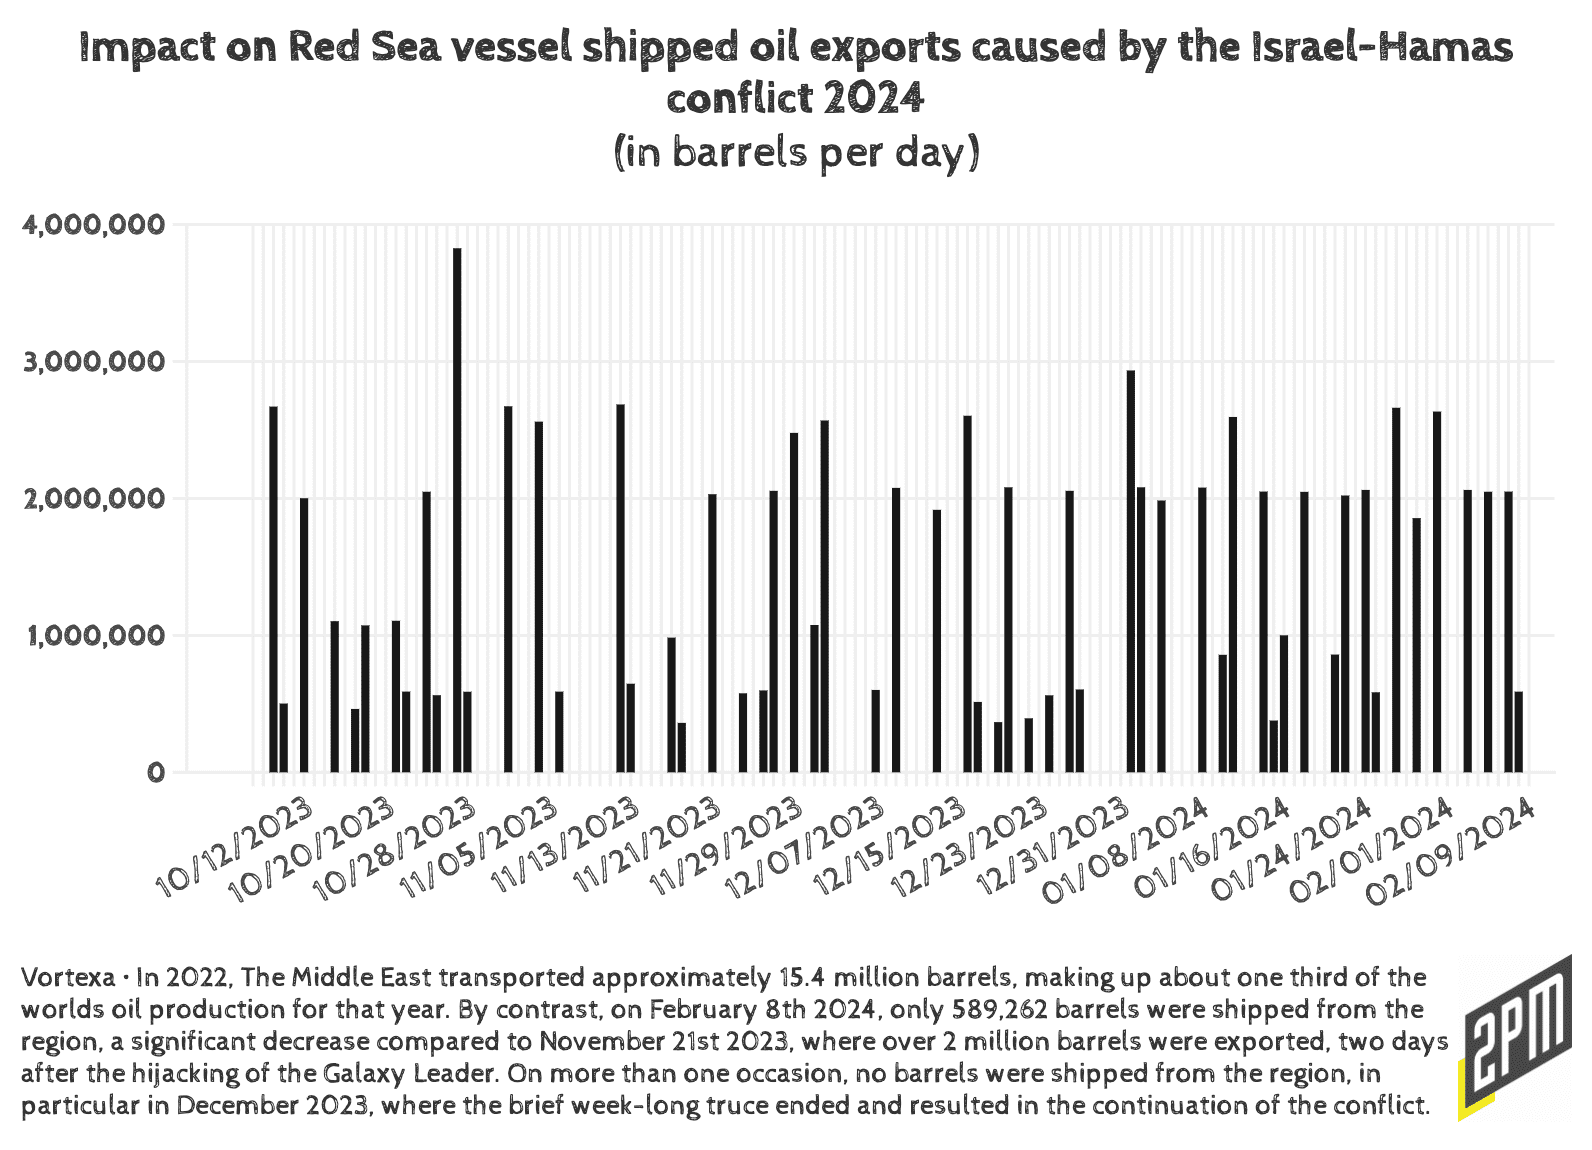
The geopolitical importance of the Suez Canal persists, with Egypt leveraging the canal’s strategic location to bolster its economy through toll revenues and related services. The canal continues to be a focal point for international trade, handling approximately 12% of global trade and a significant portion of the world’s oil shipments. Recent missile and drone attacks by Houthi rebels along the canal have caused many shipping companies to avoid the route, leading to a 67% drop in container shipping as of late January 2024. In 2023, the Suez Canal facilitated the passage of approximately 23,851 ships carrying well over a billion tons of cargo.

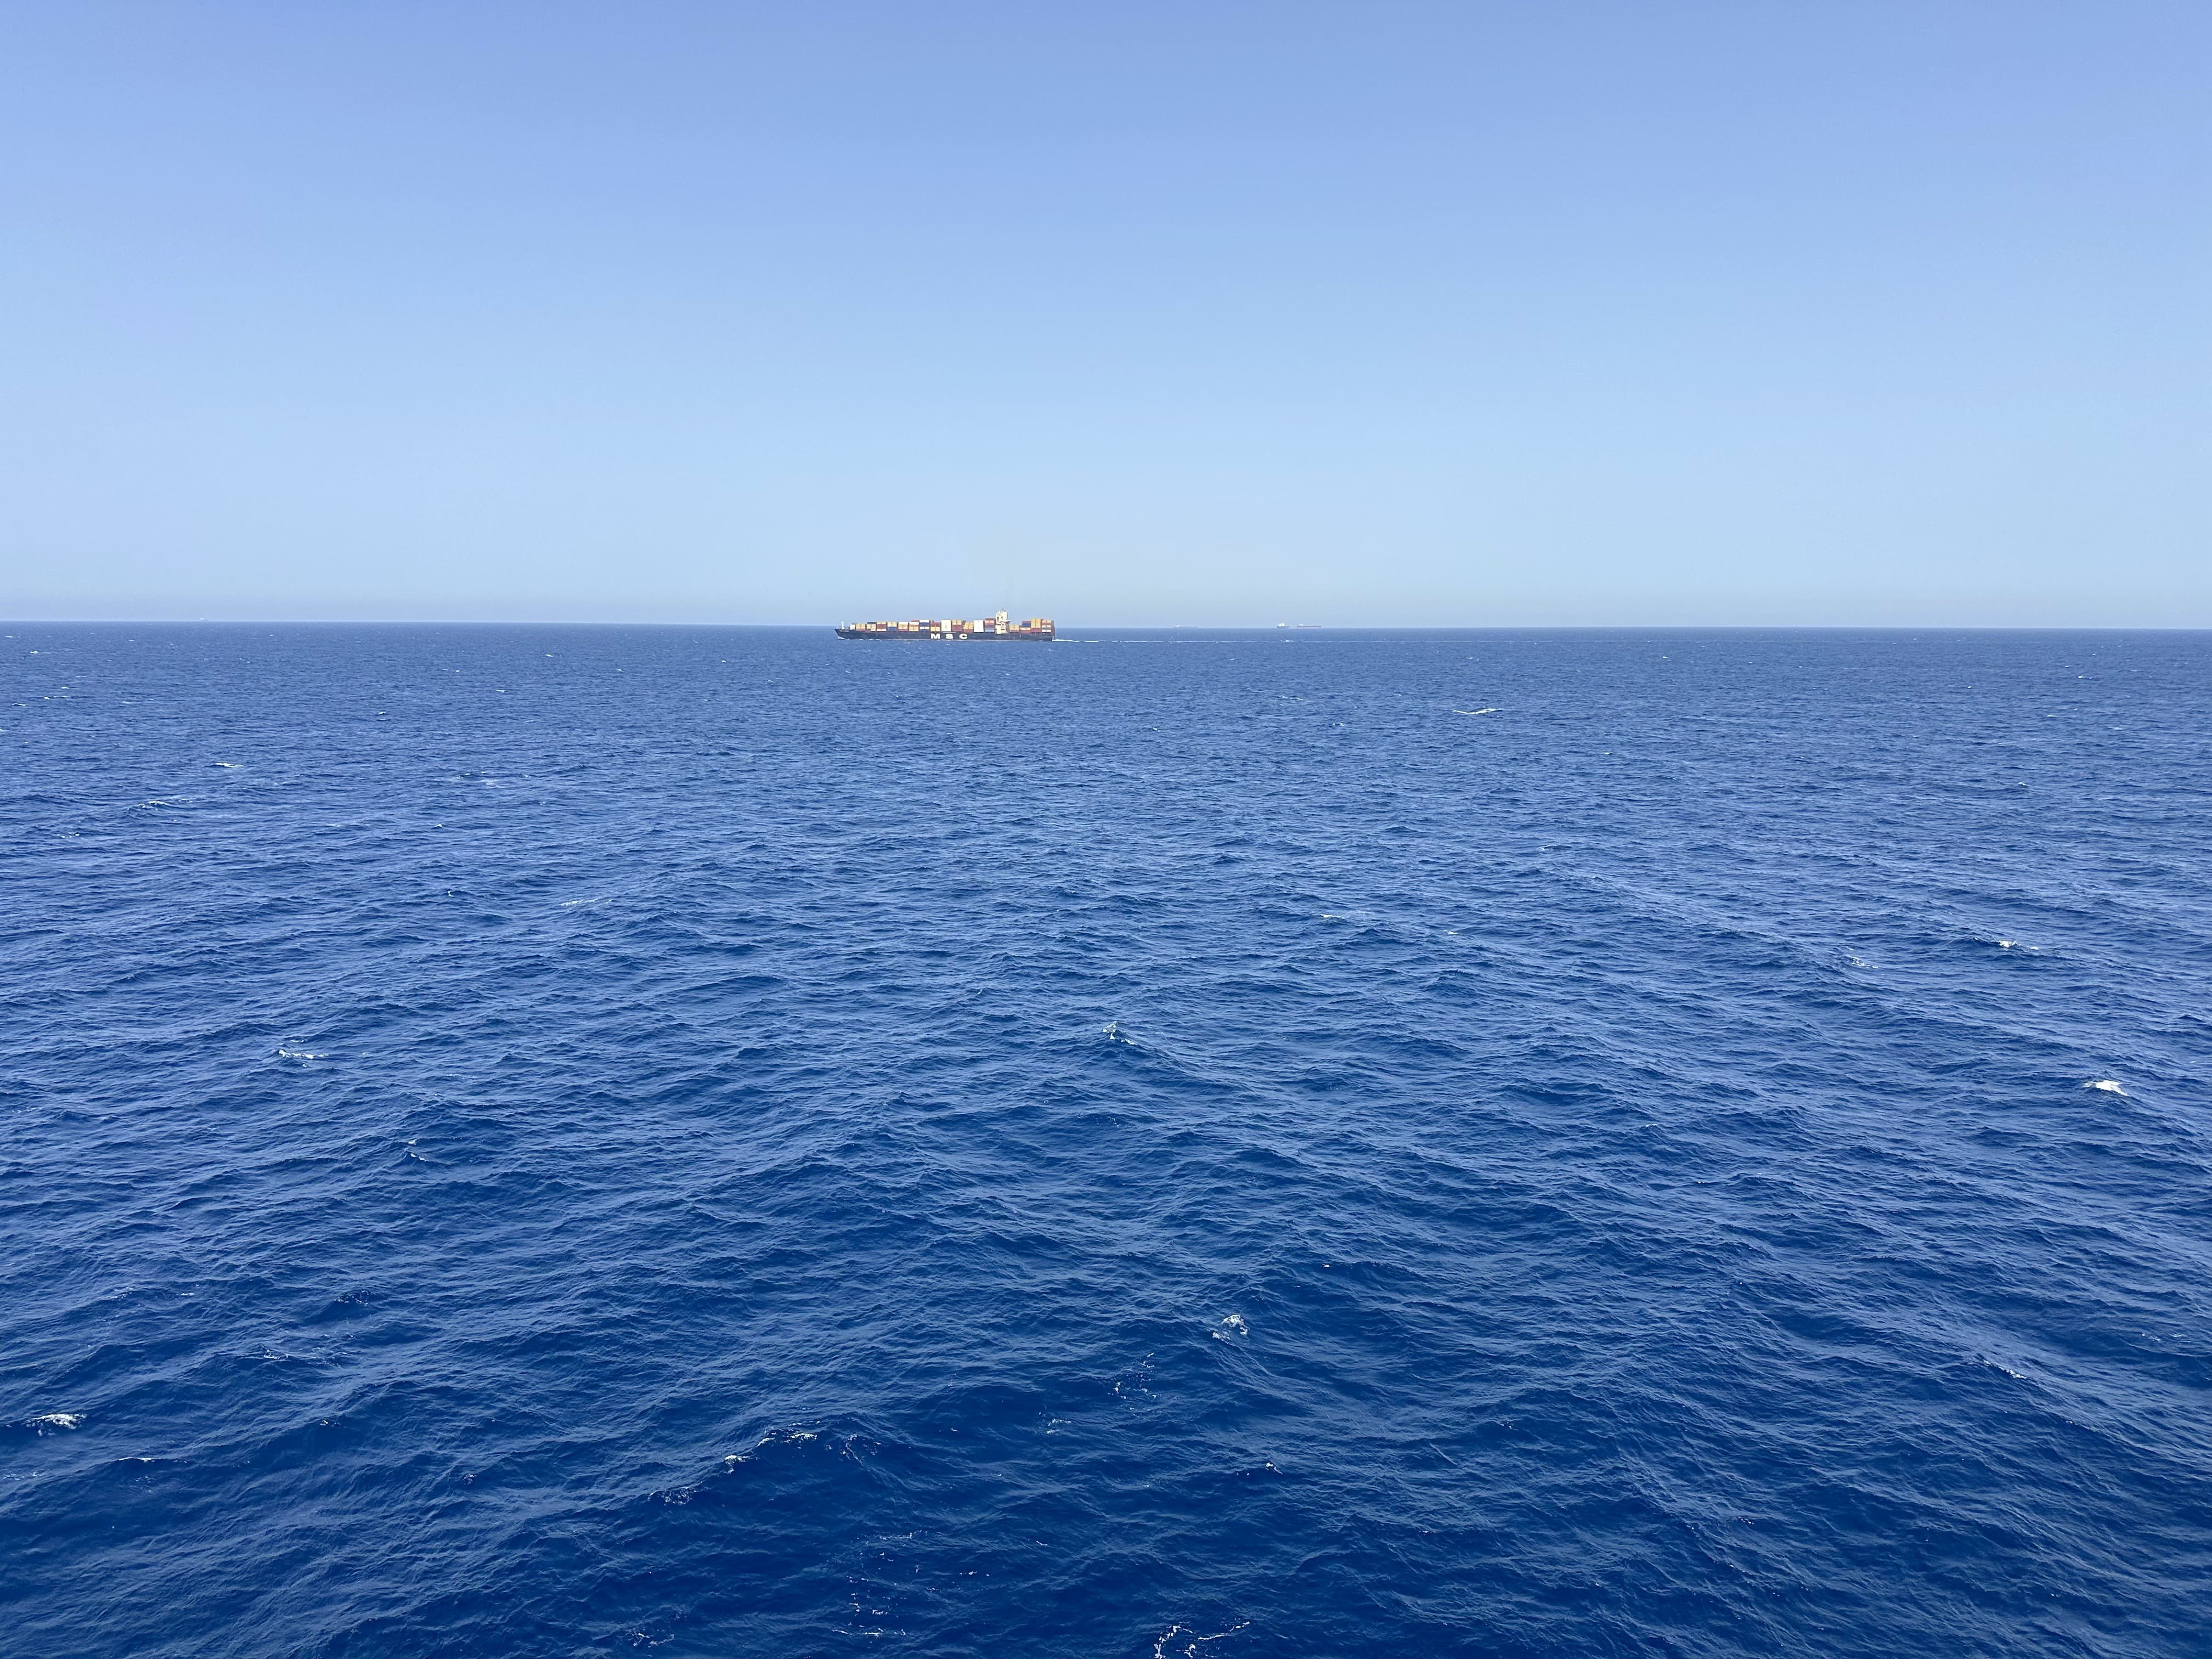
A Mediterranean Shipping Company vessel, somewhere off the coast of Turkey (taken May 20th from a passing ship)

In December of 2023, the Mediterranean Shipping Company (MSC) diverted its container ship traffic away from the Red Sea. However, it appears that MSC has returned to running some of its ships through the canal despite risk of attack.

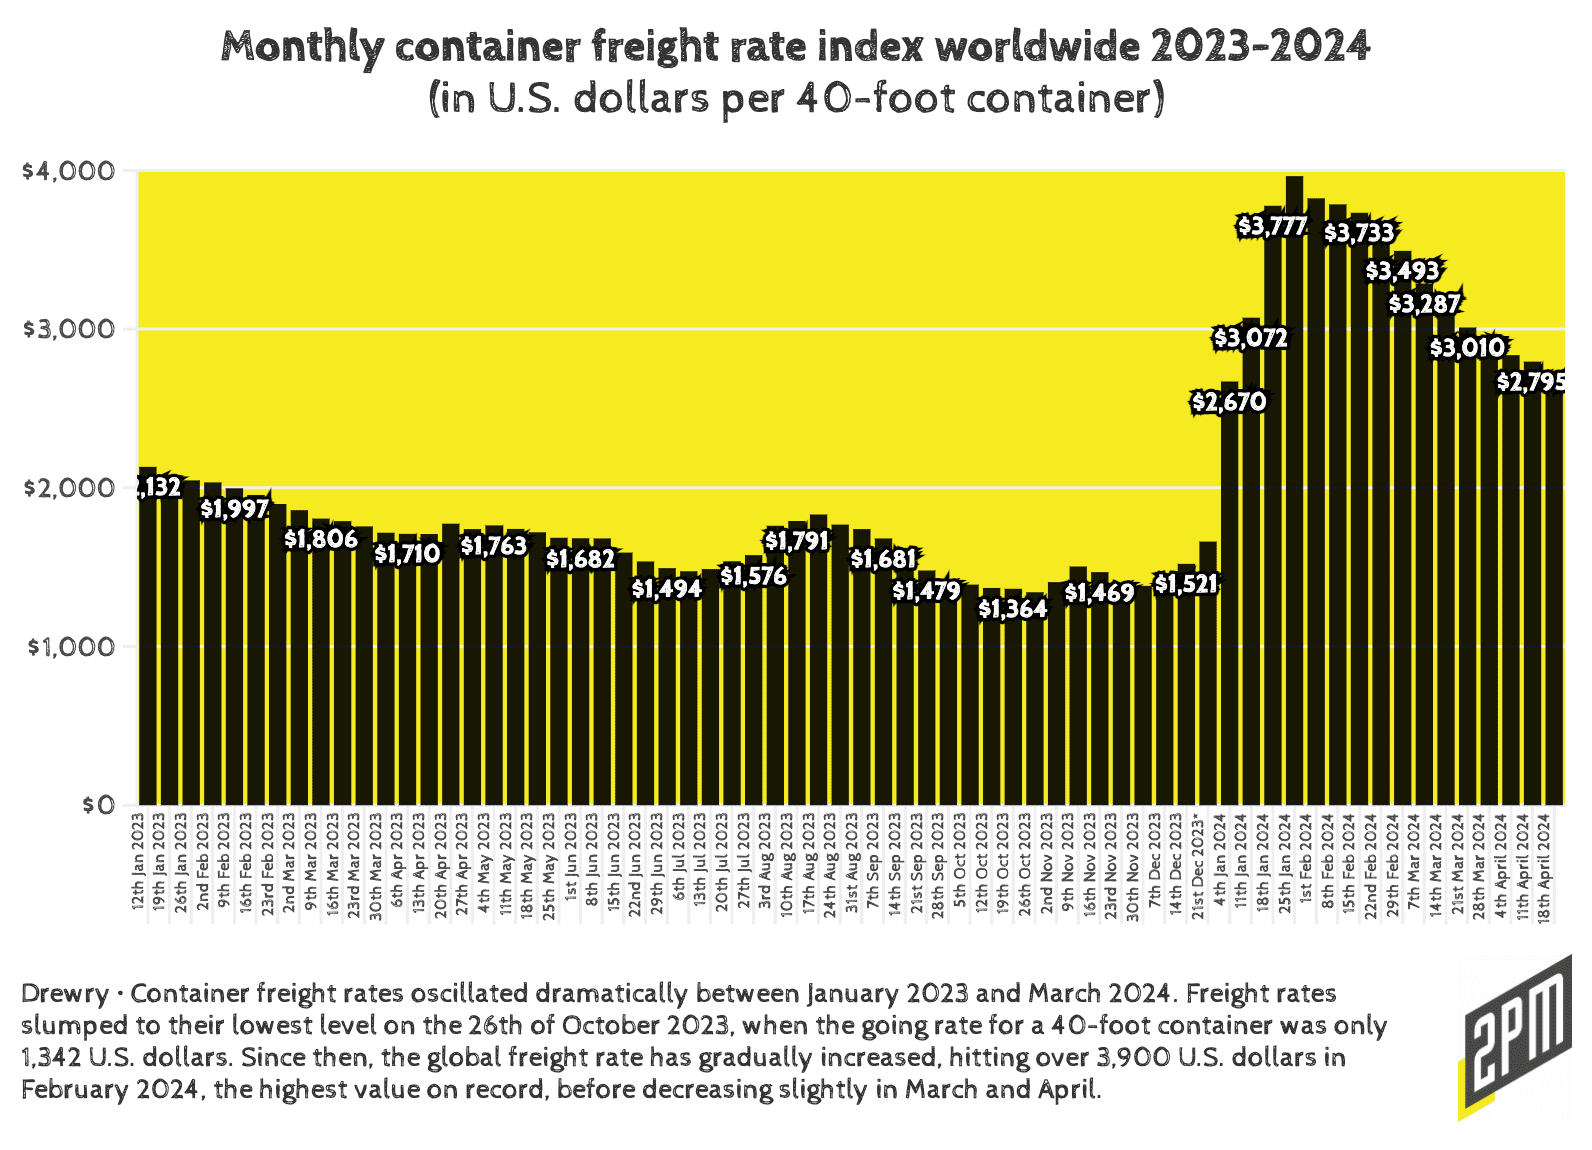
In response to the same increased threat, global shipping giant Maersk began rerouting its vessels around the Cape of Good Hope in March, significantly extending transit times between the U.S. East Coast and regions such as India and the Middle East by one to two weeks. This diversion, along with disruptions in the Black Sea due to the Russian invasion of Ukraine, has caused shipping costs to rise. According to the United Nations, container freight rates on Asia-Pacific to Europe routes have surged since November, with rates from Shanghai more than doubling by early February 2024.

Ryan Petersen on Twitter: “Global containerized ocean freight prices are surging to levels not seen since the pandemic supply chain crunch. Some key trade lane rates are up 140% since mid-December and increasing by the week. What’s happening, why, and what it means for businesses needing products moved? 🧵 pic.twitter.com/YDPKeipbMz / Twitter”

Global containerized ocean freight prices are surging to levels not seen since the pandemic supply chain crunch. Some key trade lane rates are up 140% since mid-December and increasing by the week. What’s happening, why, and what it means for businesses needing products moved? 🧵 pic.twitter.com/YDPKeipbMz

As projected, global containerized ocean freight prices have surged to unprecedented levels. Key trade lane rates have increased by 140% since mid-December 2023, echoing the pandemic supply chain crunch. Several factors contribute to this surge.

Global Factors (A-H)

A. Firstly, the demand for freight shipping remains largely inelastic as Peterson notes in his thread. Businesses do not significantly alter their shipping volumes based on freight costs, leading to price spikes when demand exceeds supply. This inelasticity has been a significant factor in the current price surge. Here’s some interesting data from Drewry:

Freight rates from Shanghai to Rotterdam, Shanghai to Los Angeles, and Shanghai to New York increased 12% to $4,172, $4,476 and $5,717 per 40ft container respectively. Similarly, rates from Shanghai to Genoa increased 11% or $481 to $4,776 per feu. Likewise, rates from Rotterdam to New York climbed 2% or $49 to $2,209 per 40ft box. […] Drewry expects ex-China freight rates to rise due to increased demand, tight capacity, and the need to reposition empty containers.

B. Beginning in December, terrorist activity in the Red Sea compelled global container ships to reroute around Africa. This change in route significantly reduced shipping capacity, as the journey from Asia to Europe now takes 30-40% longer to complete, effectively diminishing the overall throughput of the shipping network.  Consider this from IMF blog: 

This increased delivery times by 10 days or more on average, hurting companies with limited inventories.

C. Severe weather conditions in major ports such as Shanghai, Ningbo, Malaysia, and Singapore have exacerbated port congestion, further straining the already limited shipping capacity. The interplay of natural disasters, including droughts and heavy rain, has disrupted operations and increased delays​. The Journal of Commerce on this:

Fog is the main problem at ports in China, including Shanghai and Ningbo. […] The adverse conditions meant vessels could not berth even as more ships arrived at anchorage, leading to vessel bunching that exacerbated port congestion.

D. As the potential Canadian rail worker strike looms, U.S. West Coast freight facilities are under pressure as shippers divert containers to avoid disruptions. This adds to existing challenges like increased rates at the Port of Norfolk and container dwell issues in Los Angeles and Long Beach. The strike threatens to exacerbate congestion and equipment imbalances, affecting operations in Dallas and the US Midwest. ITS Logistics recommends strategies to mitigate delays, including terminating imports at ports and using transloading and one-way trucking.

Concerns over a potential Canadian rail strike have disrupted North American supply chains, compelling importers to reroute goods through U.S. gateways, adding to the congestion. This rerouting has caused significant delays and increased costs for businesses reliant on these supply routes​. From DC Velocity:

The impact comes amid additional supply chain impacts such as significant rate increases in dray and container storage capacity at the Port of Norfolk as demand shifts are spreading along the U.S. Eastern Seaboard to absorb Baltimore cargo​.

E. The U.S. East Coast faces a confluence of issues, including drought-induced capacity reductions at the Panama Canal and port access disruptions following the Maersk MV Dali incident in Baltimore. Additionally, the impending expiry of the International Longshoreman Association’s contract has fueled fears of delays during peak shipping season​.

F. The Asia to Europe trade routes have seen substantial rate increases, with the Shanghai Containerized Freight Index (SCFI) showing a 155% rise in prices since mid-December. Transpacific lanes are also affected, as carriers reallocate ships to cover gaps in Asia-Europe routes, causing a 142% rate increase for shipments from Shanghai to the U.S. West Coast​. You can view spot freight rates here.

G. Businesses face higher freight costs and potential delays, prompting them to expedite shipments, which can lead to panic bookings and further congestion. The introduction of Peak Season Surcharges (PSS) on fixed-rate contracts has compounded these challenges, aligning fixed rates closer to volatile spot market prices​. This November 2023 Supply Chain Dive report tuned me into the idea of this happening sometime in 2024 (before the actual peak season begins).

H. The high freight rates signal to carriers the need for increased capacity. New container ships, ordered since the COVID-19 pandemic, are expected to bolster capacity in the coming years, potentially alleviating some of the current pressures. Drewry’s World Container Index indicates a substantial increase in shipping capacity expected by the end of 2024​. In the meantime, companies may need to adopt premium shipping options to prioritize cargo, albeit at higher costs. Agility in logistics planning becomes crucial, as businesses must navigate unpredictable disruptions and maintain supply chain resilience​.

These heightened costs and delays are expected to eventually impact consumers and farmers, highlighting the far-reaching effects of geopolitical instability on global trade routes and the importance of the Suez Canal in maintaining efficient international commerce.

Best Practices Moving Forward

Businesses have to enhance their logistical agility and prepare for both anticipated and unforeseen disruptions. This involves diversifying supply chains geographically to reduce reliance on single points of failure. Investing in digital tools and technologies for better visibility and agility in logistics planning is crucial. The rise of smart containers and the standardization of electronic bills of lading are examples of how technology can enhance efficiency and resilience​. Eric Linxwiler, Senior Vice President of TradeBeyond:

If there’s one lesson supply chain managers have learned from recent disruptions, it’s to always be prepared for the unexpected. Ongoing disturbances in the Red Sea shipping lane are anticipated to extend well into 2024, with little hope for cessation of the conflicts, underscoring the critical need for agile, technology-driven strategies that can adapt to the unforeseen.

Furthermore, fostering collaboration between national security experts and commerce professionals is essential to develop comprehensive strategies that address both economic and security concerns.

The surge in global containerized ocean freight prices underscores the fragility and complexity of the global shipping industry. While capacity expansions offer a glimmer of hope, the enduring lesson is the necessity for resilience in the face of an ever-changing global trade environment. The effects of the forecast made in December 2023 have come to pass, highlighting the importance of foresight and strategic planning in mitigating the impacts of global disruptions.

In a world where the stakes have never been higher, the challenge posed by these disruptions is unparalleled. The events unfolding on the global stage in 2024 will undoubtedly be shaped by the continued, intricate dynamics of this changing geopolitical landscape, affecting not only the global economy but also the sovereignty of nations and its citizens. The insights and developments from the first half of 2024 reinforce the need for businesses and policymakers to remain agile and vigilant in the face of ongoing and future challenges.

By Web Smith

Deep Dive: Value and Volatility (CPG Lending)

In the dynamic landscape of fintech lending, one leading lender initiated a strategic collaboration with 2PM. This partnership aimed to leverage 2PM’s deep insights into consumer behavior and brand performance, utilizing key data points to refine lenders’ approaches to credit offerings.

By analyzing detailed market data, the lender was better positioned to assess the financial health and potential of individual brands, enabling more informed decision-making processes. This collaboration not only underscores this particular lenders’ commitment to “outside-of-the-box” data-driven strategies but also enhances their capability to support sustainable brand growth in an increasingly competitive market. All is not well in the market.

Confirmed by subsequently published reports, the pressure on fintech lenders like Ampla is mounting. This is evidenced not only by their reported financial struggles but also by the outreach from competitors seeking to capitalize on Ampla’s vulnerabilities. A recent LinkedIn post by a Paperstack employee highlighted the concerns within the CPG industry and their competitor’s potential failure. It specifically acknowledged the deep financial challenges Ampla might be facing and extending a helping hand to those affected. This situation underscores a larger trend in the fintech sector, where companies are both competitors and crucial lifelines, offering necessary capital to businesses navigating the capital-intensive journey of eCommerce.

By analyzing detailed market data, the lender was better positioned to assess the financial health and potential of individual brands, enabling more informed decision-making processes. This collaboration not only underscores this particular lenders’ commitment to “outside-of-the-box” data-driven strategies but also enhances their capability to support sustainable brand growth in an increasingly competitive market.

****

Ampla’s notable clients include:

  • MrBeast Feastables: A brand launched by the YouTube personality MrBeast, focusing on snacks.
  • Cuts: A clothing brand known for its high-quality men’s shirts.
  • Serenity Kids: A company that produces baby food.
  • Hatch: A brand offering sleep-related products.
  • Recess: A beverage company specializing in sparkling water infused with hemp and adaptogens.
  • Glamnetic: A beauty brand known for magnetic eyelashes.
  • Maev: A pet food company that provides raw dog food.
  • MM.LaFleur: A women’s clothing brand focusing on professional attire.
  • Toybox: A company that offers 3D printers designed for kids.
  • Wandering Bear: A coffee brand offering cold brew coffee.
  • Stately: A men’s fashion subscription service.
  • &Collar: A sustainable clothing brand.

****

According to recent reports, the pressure on fintech lenders like Ampla is mounting. This is evidenced not only by their reported financial struggles but also by the outreach from competitors seeking to capitalize on Ampla’s vulnerabilities. A recent LinkedIn post by a Paperstack employee highlighted the concerns within the CPG industry and their competitor’s potential failure. It specifically acknowledged the deep financial challenges Ampla might be facing and extending a helping hand to those affected. This situation underscores a larger trend in the fintech sector, where companies are both competitors and crucial lifelines, offering necessary capital to businesses navigating the capital-intensive journey of eCommerce.

In addition to this particular blog from Paperstack, I’ve personally received similar messages a few of Ampla’s other competitors, each presenting their services as stable, long-term financial solutions. Other publications and smaller consultancies have reported similar activity. These interactions tell a tale. For one, they mark a significant shift in how digital capital is being approached in today’s market. The competitive market was difficult for these lenders, as early as February 2023 (according to this Betakit report on the growing lender – Paperstack). It can only be more difficult now.

Amid these conditions, Toronto’s Clearco and Dublin-based Wayflyer—two of the biggest FinTech firms providing revenue-based financing to e-commerce brands—have undergone significant layoffs. In Clearco’s case, the company has also changed CEOs and exited overseas markets, handing this portion of its business to London-based competitor Outfund.

The much smaller Paperstack faces the same conditions that forced bigger players to regroup, from mounting inflation and interest rates, which have made it difficult for many startups to raise capital, to slowing e-commerce growth.

Fintech lenders are operating in an even higher-pressure environment marked by several intersecting challenges:

Macroeconomic Shifts: The end of historically low interest rates has significantly impacted fintech lenders, increasing their cost of capital and forcing them to reassess their lending models. As borrowing becomes more expensive and economic growth cools, both lenders and borrowers face heightened financial stress.

Increased Competition: As traditional banks tighten their lending standards, more businesses have turned to revenue-hungry fintech startups for solutions, intensifying the competition among these lenders. Each platform strives to offer more attractive, flexible, and innovative financing solutions to stand out, as evidenced by the proactive outreach efforts from companies like Paperstack, Ampla, Kickfurther, Clearco, Shopify, Stripe, and others.

Sector-Specific Challenges: For fintechs focusing on CPG brands, like Ampla, the shift in consumer behavior towards more cost-effective purchasing and the rise of white-label products presented additional hurdles. These changes affect the financial stability and growth prospects of their clientele, directly impacting the risk assessments and business models of the lenders.

Regulatory Environment: Increasing scrutiny from regulators on lending practices adds another layer of complexity, pushing fintechs to innovate within the confines of new financial regulations. This requires continuous adaptation and compliance efforts, further straining their resources.

Technological Advancements: To stay competitive, fintech lenders must continuously invest in technology to improve their financial products and services. This includes enhancing risk assessment models with AI and machine learning, and developing more user-friendly platforms that can integrate seamlessly with the businesses they serve.

These challenges collectively contribute to the high-pressure environment that defines the new era of digital capital. Fintech lenders are not only required to be financially robust but also agile and innovative, capable of quickly adapting to changing market conditions and customer needs.

The public and private outreach from companies like Paperstack is indicative of the broader strategic shifts occurring within the fintech sector. As companies vie for leadership in this tumultuous market, their ability to provide reliable, flexible, and efficient financial solutions will likely determine their success. For consumer businesses reliant on these financial services, the landscape offers both potential risks and rewards, emphasizing the importance of choosing partners that align with their long-term financial goals and operational needs.

The Core Target of the Fintech SAAS Lender

The core target industry is undergoing significant transformation due to evolving consumer behaviors and economic pressures, which in turn are impacting the CPG lending industry. In a recent deep dive on CPG, I reported:

The landscape for CPG brands is undergoing a seismic shift, marked by increased challenges in distribution avenues, market consolidation by retail giants, diminishing venture capital interest, and heightened cost pressures. This confluence of factors is rapidly closing the window of opportunity for CPG brands to achieve widespread distribution and visibility.

As the financial landscape shifts, fintech companies that specialize in lending to CPG brands are facing unique challenges but, also, new opportunities that necessitate strategic adaptation to stay competitive and relevant. Here are the key points influencing the changing role that debt financing is playing in the role of CPG brands and beyond.

By nature, this makes debt a much higher risk to the brand and the lender.

As eCommerce continues to expand, small retailers are finding the space increasingly challenging to navigate, contrary to the expectations set by eCommerce’s growing adoption. This complexity is rooted in various structural changes in consumer behaviors, market dynamics, and intensified competition, particularly from dominant industry players.

The CPG Struggle

The story of Foxtrot Market’s failure illustrates a critical issue many small eCommerce retailers face: misalignment with consumer expectations. Foxtrot aimed to differentiate itself with a unique, upscale product mix and aesthetic appeal but neglected to integrate essential items that meet daily consumer needs, which are crucial for driving repeat business in the convenience sector. This example highlights a broader narrative where small retailers struggle to balance unique offerings with the essential expectations of convenience and necessity. Their focus on specialty items rather than staples, combined with high operational costs from city center locations, rendered Foxtrot’s business model unsustainable in a highly competitive market.

Moreover, the digital advertising landscape, once a boon for small eCommerce ventures, has become prohibitively expensive. As costs escalate—with 96% of CPG companies managing spends across multiple networks—the already tight budgets of smaller players are further squeezed. Additionally, the consolidation of market power by retail giants such as Walmart, Costco, and Kroger further narrows the window for smaller brands to gain visibility and shelf space. Data show a significant concentration of CPG spending among these major players, which captures a substantial portion of U.S. CPG expenditures, creating formidable barriers for smaller companies.

Evolving consumer preferences complicate the entry of new or smaller brands into the market, particularly the preference for purchasing groceries from established retailer websites over new online marketplaces or direct brand channels. As eCommerce grows, especially in sectors like food and beverage, small retailers must navigate the challenging waters of gaining consumer trust and visibility amidst dominant competitors.

The landscape for entering eCommerce has also become tougher, with diminishing venture capital interest in new, unproven markets. The shift in economic conditions, increased interest rates, and a demanding profitability path have led to a more cautious approach from investors. This financial backdrop makes it increasingly difficult for small eCommerce retailers to secure the necessary capital for growth and sustainability. By nature, this makes debt a much higher risk to the brand and the lender.

Another dimension of the challenge for small retailers is the blurring of lines between high-end and mass-market offerings on major e-commerce platforms. The presence of luxury brands on platforms like Walmart underscores the difficulty of maintaining brand integrity and visibility in an overcrowded online space. This juxtaposition creates a confusing marketplace where small retailers struggle to position themselves effectively.

In an eCommerce environment described as “junkified,” (a direct quote to Vogue Business by Neil Saunders) where the proliferation of products overwhelms consumers, small retailers must find ways to stand out. The necessity for strategic innovation, effective curation, and clear brand positioning has never been more critical. Marketplaces need to balance the breadth of offerings with curation, ensuring consumers are not overwhelmed but rather guided to quality and relevant products.

These challenges collectively depict an eCommerce landscape that is becoming more complex and less accessible for small retailers, demanding a strategic recalibration and innovative approaches to consumer engagement, product offerings, and market positioning.

Consumer Shifts to Cost-Conscious Buying

Economic constraints have led consumers to become more cost-conscious, increasingly opting for white-label or generic products over branded goods. This shift is driven by a squeeze on household budgets, where affordability has begun to trump brand loyalty. A Forbes article from May 2024 highlighted that over half of consumers are concerned about their personal finances, influencing their purchasing decisions towards cheaper alternatives. This consumer behavior shift impacts the revenue streams and stability of CPG brands, which are critical factors that lenders consider when evaluating creditworthiness.

Impact on CPG Brands and Their Financing Needs

As CPG brands adjust to these market changes, their need for flexible and responsive financing solutions increases. Traditional lending models, which rely heavily on stable and predictable revenue streams, may no longer be adequate. Fintech lenders, therefore, need to adapt their products to accommodate fluctuations in CPG companies’ cash flows and provide more tailored financing options that can adjust to a more volatile market environment.

The Role of Fintech in Adapting Lending Practices

Fintech companies like Ampla have been at the forefront of providing innovative financial solutions tailored to the needs of CPG brands; this is both a gift and a curse. These companies leverage technology and data analytics to offer dynamic credit products that can adapt to rapid changes in the market. For example, fintech lenders might use advanced underwriting algorithms that take into account real-time sales data or seasonal fluctuations, allowing for more flexible repayment terms that align with a brand’s cash flow patterns.

Increased Competition and Market Pressure

The tightening of lending standards by big banks, as reported by Bloomberg in May 2024, is creating an additional layer of complexity. As banks become more conservative in their lending practices, particularly in response to economic instability and previous bank failures, CPG brands may find it more difficult to secure traditional financing.

Lenders have generally been tightening credit standards since the second quarter of 2022, following a string of high-profile regional bank failures. The Fed lifted its benchmark rate last year to a two-decade high in a bid to curb inflation, and high borrowing costs have weighed on businesses and households.

This situation presents both a challenge and an opportunity for fintech lenders. While it opens the door for these lenders to fill the gap left by banks, it also puts pressure on them to manage risk more effectively amid an increasingly competitive landscape.

****

To effectively serve CPG brands under these new conditions, fintech lenders are increasingly looking towards strategic collaborations. For instance, partnerships between fintechs and retail data aggregators can provide deeper insights into consumer trends, brand performance, and market dynamics, enhancing the lenders’ ability to assess risk and customize financial products. Moreover, as CPG brands seek to differentiate themselves in a crowded market, fintech solutions that can support innovative retail strategies—such as DTC models and online marketplaces—become particularly valuable.

The evolving CPG industry, marked by a shift towards more price-sensitive consumer behaviors and the resultant impact on brand stability and growth prospects, is significantly influencing the CPG lending industry. Fintech lenders are responding with more adaptive, innovative, and risk-aware lending solutions that align more closely with the current needs of CPG brands, ultimately reshaping the landscape of financial services in this sector.

By Web Smith