备忘录Shopify的增长纽带是金融

The commerce, payments, and debt products industries are converging. Shopify is one of the few companies that sits at the nexus of these three.

Over the last few months, I spent a substantial amount of time preparing for and passing my Securities Industry Essentials Exam (SIE) to gain at least a rudimentary understanding of consumer, fiduciary, and monetary principles and how they impact equity and debt markets. I learned a lot along the way. The motivation was and is to understand the mechanics of financial markets with some proficiency (and maybe pursue a Series 7, who knows). As I went through this studying process, it became clear that understanding today’s online retail landscape requires a firm grasp of the financial systems.

Payments, debt, and commerce are all converging. Shopify is at its nexus.

Shopify is one company at the intersection of commerce, payments, and debt. To properly analyze the growth of companies like it, you also have to understand the financial systems that it relies on for growth businesses.

At its core, Shopify is a platform that enables small and medium-sized businesses to build and operate online stores. The company’s value proposition and its ability to support merchant growth have positioned it as a pillar of the eCommerce ecosystem. But many on the outside may not realize that Shopify’s growth trajectory is tied not just to the number of new stores it enables, but also to the financial products it offers. Shopify’s venture into lending and merchant cash advances (MCAs) through Shopify Capital has positioned it as both a commerce enabler and a financial services player.

This dual role becomes even more interesting when you consider that new store growth is slowing, as indicated in its most recent earnings call. While Shopify remains a dominant force in eCommerce, the platform is maturing. The initial and later surges of new store creations, the latter driven by a combination of pandemic-driven digital adoption and Shopify’s user-friendly interface, has naturally slowed. Today, the company faces a new challenge: sustaining growth not through the sheer number of stores created, but through deepening its relationships with existing merchants, which is where its Capital division becomes crucial.

Shopify Capital: The Key Growth Business

In 2024, Shopify Capital became an understated yet vital piece of Shopify’s growth strategy. In Q2 of this year, Shopify originated $700 million in loans. Shopify CFO Jeff Hoffmeister referred to this arm of the company as a “growth business,” highlighting its increasing importance. Yet, despite these numbers, Shopify has downplayed the role of Capital in its overall strategy, a stark contrast to earlier years when it would broadcast the growth of its lending arm during earnings calls. Amazon followed a similar model, until recently. It now refers its clients to third-party lenders.

One of the reasons for Shopify’s newfound reticence could be tied to market conditions. With U.S. credit card debt reaching a record $1.14 trillion by Q2 2024 and delinquency rates rising, the financial environment is becoming increasingly precarious for both consumers and small businesses. Shopify’s merchants, most of whom are small businesses, are particularly vulnerable to these macroeconomic trends. Shopify’s hesitation to promote its lending growth could be a protective measure, shielding itself from scrutiny should the economic environment worsen, leading to higher default rates among its loan recipients.

Financial Strain and the Broader Economic Picture

To truly understand the risks Shopify faces, it’s essential to look at the broader financial landscape. The latest data from the Federal Deposit Insurance Corporation (FDIC) shows a sharp increase in past-due and nonaccrual rates for non-owner occupied, nonfarm, nonresidential loans, particularly for banks with assets exceeding $250 billion. This indicates stress in the commercial real estate market, a crucial segment for many small business owners, particularly those operating physical stores.

Source: FDIC

Shopify Capital’s loan recipients, who are predominantly online merchants, might seem insulated from this trend, but they are not immune to broader economic pressures. Rising consumer debt levels signal that end customers may reduce discretionary spending, which directly impacts Shopify merchants’ revenue streams. If consumers tighten their belts, small businesses – many of which operate on razor-thin margins – will struggle to maintain cash flow, driving demand for short-term capital (often MCAs) to bridge gaps in revenue.
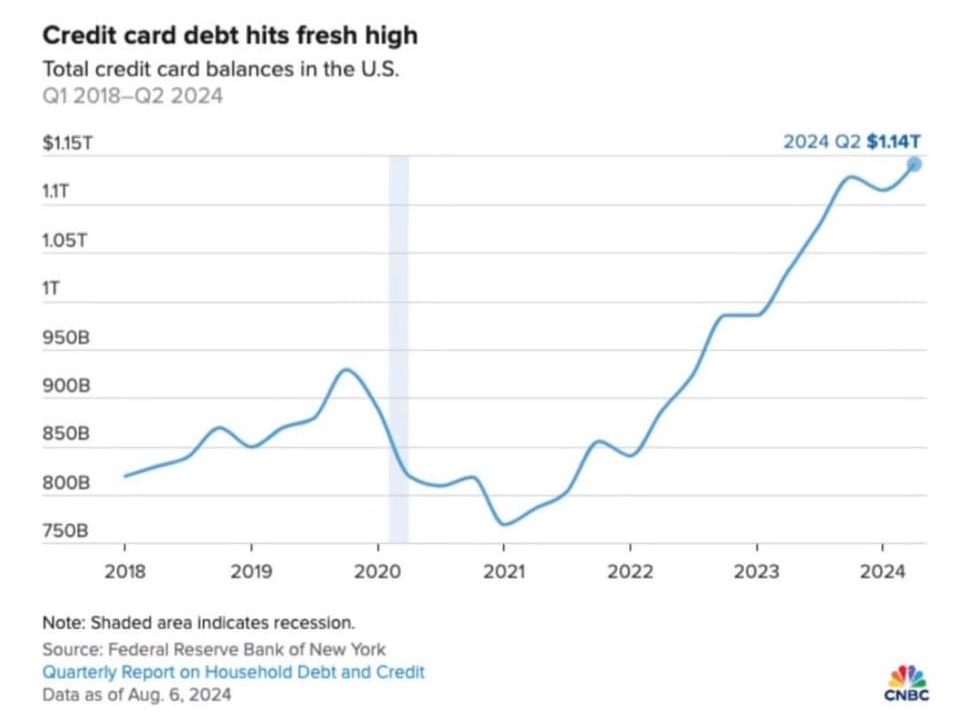
Source: CNBC

This increased demand for Shopify’s primary growth market, MCAs, comes amidst heightened risk. The more merchants turn to Shopify for financial support, the greater Shopify’s exposure to potential defaults, especially as economic conditions worsen. In an environment where loan delinquencies are rising across the board, Shopify will need to strike a careful balance between sustaining growth through lending and managing the risk that accompanies it.

A Shift in Growth Strategy: Beyond New Store Creation

The slowing growth in new store creation means that Shopify can no longer rely on onboarding new merchants to fuel its financial growth. Instead, it is now identifying clients from existing legacy platforms. Additionally, the company is maximizing the value of its existing merchant base while helping each of these merchants find new ways to drive their own increase in revenues. This is where the intersection of commerce, payments, and debt becomes critical. Shopify is no longer just a commerce platform; it has evolved into a multi-faceted financial services provider, using its intimate knowledge of merchants’ sales data to offer targeted lending products.

By leveraging its financial data and payment processing capabilities, Shopify has created a flywheel effect. It enables merchants to grow their businesses, process payments through Shopify Payments, and then access capital through Shopify Capital when needed. This ecosystem not only ties merchants deeper into the Shopify platform but also creates multiple revenue streams for the company. However, this financial flywheel is not without its challenges during periods of systemic risk.

As consumer and commercial debt levels rise, Shopify faces increasing risk exposure. The company’s balance sheet shows $815 million in loans and MCAs as of Q1 2024, a slight decrease from the previous quarter ($816 million). While Shopify has yet to provide transparency on whether it is offloading some of these receivables to banks like Synchrony, the flat growth in receivables is notable, especially in a time when demand for small business funding should be increasing.

Shopify is navigating a delicate balance. On the one hand, it must continue to grow its lending division to maintain momentum as new store creation slows. On the other hand, it must manage the growing risks associated with rising default rates and the increasing financial stress on small businesses and consumers alike.

The Road Ahead for Shopify

As Shopify’s business models continue to evolve, its future growth will increasingly hinge on its ability to operate effectively at the convergence of commerce, payments, and debt.

While the company has been quiet about its lending business in recent quarters, its growing importance is hard to ignore. Shopify Capital long represented an opportunity for the company to deepen its relationships with existing merchants, generate recurring revenue, and diversify its income streams. However, the growing risks are outside of Shopify’s control and the company will need to be vigilant in managing its exposure to defaults as economic pressures mount.

In an environment where financial literacy is becoming a crucial part of understanding company growth, Shopify serves as a prime example of how deeply intertwined commerce and financial services have become. Understanding the company’s future means not only tracking new store growth but also keeping a close eye on its balance sheet, its lending practices, and the broader economic conditions that will shape the trajectory of the industry’s major players.

韦伯-史密斯的研究、数据和写作
未来:TipTop 或将重新定义支付技术

In December of last year, I proposed a novel concept to a returns management software company. I suggested that adding an exchange function to their technology stack would shape the industry by promoting a method of reCommerce and a post-purchase marketplace led by the company’s many direct-to-consumer clients currently using the software to simplify returns.

The idea’s crux was built on a critical issue rapidly gaining momentum: microplastics management. This environmental challenge pushes companies to reconsider their approach to product returns, recycling, and resale. The essence of my proposal was simple: companies need systems to upcycle and recycle materials, leveraging these efforts for tax incentives, public goodwill, or even profit. I ended the proposal with the following words (edited for brevity):

This idea is infinitely scalable and will be a prominent business with or without [company]. But you are positioned with several advantages and a head start to include: existing portfolio of companies to offer the service, a brand that suggests the power of upcycling, a network of potentially interested partners who can help you facilitate. I just happen to believe that this can transform [company] – moving it to a higher plane. And it can transform the industry that I love with all of my heart.

The proposal was scalable, innovative, and essential to addressing the growing microplastics crisis in the fashion industry. My proposal to the returns management company was not accepted. Fast-forward to the fourth quarter of 2024 and a better solution has been brewing for nearly three years. TipTop is a venture-backed development billed as a payments solution from Postmates founder Bastian Lehmann.

Recycled goods can be a downpayment on future purchase.

Lehmann’s TipTop is taking bold steps to reimagine the lifecycle of consumer goods: how they’re sold, acquired, and ultimately resold or recycled. With the rise of reCommerce (the resale of products), TipTop’s new payment system is an answer to a forward-thinking vision, one that aligns sustainability with profitability in the world of fast-moving consumer goods. Tiptop is designed to make it easy to resell and repurpose items and is not only a business model innovation but it can be a solution to an environmental dilemma that has been long overlooked until recently. On September 24, The Guardian published this legislative news on textiles in the state of California:

If passed, Californians will be able to bring unwanted and even damaged apparel and household textiles to thrift stores, charities and other accessible collection sites throughout the state for sorting and recycling. This first-in-the-nation bill, known as the Responsible Textile Recovery Act, requires producers of apparel, towels, bedding and upholstery to implement and fund a statewide reuse, repair and recycling program for their products. [cite]

It doesn’t require tremendous vision to see how TipTop’s payments architecture could replace altruism-alone for a more profitable version.

How It Works: The Power of TipTop’s Payment System

TipTop’s system addresses a fundamental problem in the retail ecosystem: it’s easier to buy than it is to sell. Consumers accumulate products—tech gadgets, clothing, accessories—often with no clear pathway for reselling or discarding them responsibly. Lehmann identified this gap and seized upon the opportunity to create a two-pronged platform that leverages consumer habits for both immediate monetary returns and longer-term resale plans.

With TipTop, users can receive instant cash offers for their old products, like electronics or fashion items, simply by connecting their Gmail or Amazon accounts. The platform scans for eligible items and predicts their resale value. This seamless experience removes the friction of traditional resale models, where consumers often have to stage, price, and list their items across multiple platforms like eBay or Facebook Marketplace. TipTop brings liquidity to this otherwise sluggish market, offering sellers cash in hand, while a delivery service picks up the product.

But TipTop’s real innovation is its payment solution, TipTop Pay, where the system allows buyers to receive an upfront discount on new items in exchange for committing to return them after a fixed period. This introduces an entirely new way to think about consumption—a shift from ownership to usage, akin to the “buy-now-pay-later” models that have reshaped retail finance. TipTop resells these items in bulk to wholesalers or via third-party marketplaces like eBay, creating a virtuous cycle of consumption and resale. If this vision can become a reality – at scale – it will revolutionize retail in ways yet to be seen.

For brands, this model is a game-changer. They can capture value from products after their initial sale, extending the lifecycle of goods and reducing the environmental impact associated with waste and overproduction. The speed of liquidity for the consumer is the “killer app.” And back to that sense of altruism, this concept ties directly to the need for sustainable initiatives I outlined in my original proposal: brands must move toward recycling, upcycling, and innovative disposal methods for microplastic-laden products to remain competitive and appease a more eco-conscious consumer base.

ReCommerce and Environmental Responsibility

The rise of reCommerce, or the resale of goods, is not just a trend but a critical business strategy for fashion and consumer brands navigating an era of heightened environmental awareness. As I noted in my 2023 study on the subject, the fast fashion and athleisure sectors are facing increasing scrutiny for their reliance on non-biodegradable synthetic fibers. By 2050, it’s estimated that 590 million tons of plastic will be produced annually, much of which will end up in landfills or the ocean.

Legislative intervention, such as the aforementioned California’s Responsible Textile Recovery Act, is creating pressure for brands to address the environmental impact of their products. TipTop’s solution offers the path forward without relying on government, enabling brands to monetize the resale of their products while simultaneously contributing to a reduction in waste. By simplifying the process for consumers to return goods, and by providing a scalable marketplace for brands to resell items, I believe that TipTop aligns financial incentives with environmental responsibility.

This connection between reCommerce and sustainability is already evident in the actions of major players in the retail space. Brands like Patagonia, Levi’s, and Nike have introduced their own resale platforms, recognizing that the resale value of their products is an important metric for both sustainability and consumer loyalty. However, for smaller brands without the resources to build proprietary resale platforms, a solution like TipTop offers the same benefits without the infrastructure investment. And even the larger enterprise brands don’t have veriable, speedy liquidity built into their models.

A Solution for Microplastic-Fueled Industries

Industries heavily reliant on synthetic fibers: athleisure, fast fashion, and performance wear – are the most at risk in this new regulatory environment. As consumers become more aware of the health risks associated with the build up of microplastics in landfills and waterways, and as governments begin to legislate against this accumulation, brands will need systems in place to manage product lifecycles responsibly.

TipTop’s resale model offers a unique advantage for these brands. By facilitating the resale of synthetic products, it extends their lifecycle, potentially offsetting the negative environmental impact of their initial production. Moreover, as brands adopt recycling and upcycling strategies, TipTop’s system could evolve to accommodate returns of materials for recycling or resale: closing the loop on product lifecycles.

In this way, TipTop could answer one of the most pressing challenges facing the fashion industry: how to monetize sustainability. By creating a frictionless way for consumers to resell items, the platform not only encourages responsible consumption but also provides brands with a new revenue stream and a powerful marketing tool. Brands that adopt this model can position themselves as leaders in the sustainability space, differentiating themselves from competitors who continue to ignore the issue.

Smarter Than What I Envisioned

When I proposed to a returns management company in 2023 that they take ownership of the recycling and material return initiatives for microplastic-heavy brands, I knew that the conversation around fast fashion and environmental responsibility was only beginning. What I couldn’t have predicted was how quickly a solution like TipTop would emerge to fulfill that vision. Transactional ease for the consumer positively influences demand for the trade

TipTop represents the intersection of technological innovation and enviro-economic necessity. It’s a system that not only simplifies the resale process for consumers but also creates a viable, scalable solution for brands looking to reduce their environmental impact. Whether through electronics or fashion: the rise of reCommerce will define the next decade of retail, offering a new way for brands to engage with consumers and a new way for consumers to think about their role in the lifecycle of the products they buy.

As TipTop’s payment system gains traction, it may become the standard for brands seeking to integrate reCommerce-led sustainability into their business models. And for those brands that are ready to embrace this shift, the opportunity is clear: not only to meet consumer demand for more sustainable practices but also to monetize those efforts in ways that benefit each their bottom lines, consumers, and the planet. TipTop can shape sustainability and recommence by redefining payments.

韦伯-史密斯的研究、数据和写作

备忘录电子商务领域的经验教训

Klarna 再次掀起波澜--但这次是为了比分期付款更重要的事情。这家瑞典金融科技巨头大胆宣称,人工智能(AI)不仅是一种提升,更是未来的趋势。这种说法并不仅仅是一种营销策略;Klarna 正在根据其人工智能驱动的雄心壮志,积极重塑其员工队伍和运营模式。首席执行官塞巴斯蒂安-西米亚特科夫斯基(Sebastian Siemiatkowski)明确表示,这一转变是公司未来战略的核心,目标是将全职员工人数减少 50%以上,从 5000 人减少到 2000 人。但这对大型企业软件公司,尤其是电子商务领域的企业软件公司意味着什么呢?

Klarna 的转折点

Klarna 对人工智能的拥抱不仅限于表面的调整。该公司已经取得了实质性成果,报告称由于人工智能举措,公司收入大幅增长,运营效率显著提高。据 Siemiatkowski 称,公司可以 "用更少的资源做更多的事情"。例如,Klarna 已将员工人数从高峰期的 5000 人减少到 3800 人,并计划进一步减少这一数字。然而,尽管人力资源减少了,该公司每名员工的收入却直线上升,仅一年时间就从 400 万瑞典克朗(约合 39.3 万美元)增加到 700 万瑞典克朗(约合 68.9 万美元)。这些数字直接证明了人工智能在取代低效率、提高生产力和盈利能力方面的强大威力。

在人工智能的采用和实际应用方面,Klarna 是我们合作伙伴中的佼佼者。我们正在共同发掘人工智能在提高生产力和改善日常生活方面的巨大潜力。

Brad Lightcap,OpenAI 首席运营官

该公司最引人关注的创新是与 OpenAI 合作开发的人工智能聊天机器人。该聊天机器人处理的工作量相当于 700 名客服人员。Klarna 还预计,仅在 2024 年,其人工智能计划就能带来 4000 万美元的利润增长。虽然这展示了人工智能在运营角色中的有效性,但其意义远不止于削减成本和裁员--它凸显了人工智能显著改变企业的潜力,尤其是在 Klarna 准备进行期待已久的首次公开募股之际。

实现盈利的动力

对 Klarna 而言,追求盈利并非新鲜事。2007 年至 2018 年间,该公司每年都实现盈利,2017 年的税前盈利达到顶峰,为 5.23 亿瑞典克朗(约合 6100 万美元)。然而,在过去几年里,随着 Klarna 积极拓展新市场,公司出现了亏损。Klarna对其Visa发行的Klarna卡进行了大量投资,并进行了数次收购,包括现已解散的Laybuy新西兰分公司,力求迅速扩大规模,拓宽市场覆盖面和市场深度。抛开人工智能不谈,实体信用卡的这一举动同样引人入胜。

****

Klarna 通过 Klarna Visa 进入实体支付领域,证明了该公司将 BNPL 模式融入消费者日常生活的创新方法。Klarna Visa 与传统的信用卡不同,它不收取利息,而是将每笔消费都转化为 BNPL 交易,要求分四个双月无息分期付款。Klarna Visa 在 Visa 网络上运行,允许用户将在接受 Visa 的商家进行的任何消费转化为易于管理的分期付款计划,从而扩大了 BNPL 模式的覆盖范围和吸引力。

虽然这些举措带来了回报--例如提高了市场渗透率,扩大了 BNPL 市场份额--但larna 的战略也付出了代价。人工智能是重建盈利能力的生命线。

****

Klarna 的人工智能裁员计划

Klarna 的人工智能转型更具争议性的一点是其对员工队伍的影响。自从公司停止积极招聘非工程职位以来,员工人数的减少主要是通过自然减员实现的。离职员工不会被替代,他们的工作被人工智能工具吸收。Siemiatkowski 的 "方向性 "目标是减少 2000 名员工,这暗示着公司将进一步裁员,但他没有明确指出最后期限。

这种转变最明显的影响体现在客户服务方面。Klarna 的人工智能助理于 2024 年初推出,目前处理着公司三分之二的客户服务聊天,其效率和客户满意度与人工客服不相上下。解决客户咨询的平均时间从 11 分钟缩短到了 2 分钟,这一显著改善证明了人工智能是如何优化传统上由人类主导的流程的。

人工智能助理的成功已经超越了客户服务的范畴。通过减少对摄影师、图片库和营销机构的依赖,Klarna 节省了数百万美元,尽管规模缩小了,但营销团队的工作效率却提高了。人工智能还应用于通信、营销和法律等部门,进一步简化了运营。

Klarna 人工智能方法的挑战和缺点

尽管在财务上取得了成功,但 Klarna 在积极使用人工智能的过程中并非没有遇到挑战。在公司内部,一些员工对工作量增加感到倦怠和沮丧,因为负责处理非自动化工作的员工越来越少。员工满意度评分大幅下降,Glassdoor 的评论显示,平均评分从 2022 年的 3.8 分降至 2024 年的 3.0 分。一些评论强调了对工作量大、压力大以及缺乏加薪或职业发展的担忧。

而在外部,Klarna 声势浩大的人工智能战略也引发了公众的担忧。虽然人工智能取代工作岗位的潜力已得到广泛认可,但许多人认为快速裁员是对工作保障的威胁。虽然社交媒体放大了一些愤怒情绪,但目前还没有具体证据表明这种反弹影响了 Klarna 的销售或客户参与度。

围绕人工智能生成的内容还存在法律和道德问题。Klarna 决定减少摄影和设计等岗位的用工,这引发了有关潜在版权侵权的问题,因为人工智能生成的作品往往会复制现有材料,而没有适当的归属。Klarna 的人工智能合作伙伴 OpenAI 目前正卷入有关版权问题的诉讼中,其结果可能会影响使用人工智能的公司未来如何处理知识产权纠纷。

对电子商务和企业软件的启示

Klarna 以人工智能为主导的转型为更广泛的电子商务和企业软件行业提供了宝贵的经验。首先,它凸显了人工智能在简化运营、降低成本和提高盈利能力方面的巨大潜力。Klarna 利用人工智能不仅削减了工作岗位,还提高了从客户服务到市场营销等整个业务的效率。

对于其他公司,尤其是像 Salesforce 或 Workday(Klarna 已与这两家公司结束了合作关系)这样的大型企业,问题是如何在不影响员工士气或冒公关风险的情况下整合人工智能。在即将上市的推动下,Klarna 的做法快速而激进。虽然这种做法可能在短期内奏效,但希望采用人工智能的公司应该考虑采取一种更加稳妥的方法,在自动化与员工福利之间取得平衡。

虽然该公司已经看到了巨大的经济效益,但仍在应对员工满意度和公众看法等复杂问题。随着人工智能的不断发展,企业需要制定既能利用其优势,又能解决其潜在弊端的战略。

如果 Klarna 的人工智能趋势持续下去,我们可能会看到整个电子商务和 SaaS 领域发生重大转变。公司可能会越来越多地采用内部人工智能解决方案,从而广泛降低成本、缩减员工人数,并减少对传统第三方服务提供商的依赖。以下是 10 家 DTC 行业 SaaS 公司,它们可能会受到人工智能创新的影响,因为企业开始将这些功能引入内部,以便更有效地管理成本:

Klaviyo
人工智能的进步可以让公司在内部开发个性化的通信系统,减少对第三方解决方案的需求。

Yotpo
内部人工智能工具可以简化内容生成、评论管理,甚至是客户奖励,从而使 Yotpo 的服务变得不再必不可少。

Gorgias
借助先进的人工智能,品牌可以建立内部客户服务自动化系统,减少对 Gorgias 等平台的依赖,以管理查询和票据。

贴心
随着人工智能提高了个性化和参与度,企业可能会开发自己的短信平台,从而最大限度地减少对外部短信营销提供商的需求。

循环
人工智能驱动的解决方案可使 DTC 品牌具备内部管理退货的能力,无需外部软件即可优化物流。

客户
内部人工智能可以简化客户服务和数据管理,减少对第三方客户关系管理工具的需求。

Privy
随着人工智能增强了潜在客户生成和转化战略,企业可以在内部开发这些能力,从而不再需要 Privy 这样的外部工具。

充值
人工智能驱动的解决方案可以让企业开发和管理自己的订阅服务,减少对外部计费平台的依赖。

大胆商务
人工智能可以让企业在内部建立个性化的结账和追加销售系统,从而不再需要 Bold Commerce 这样的 SaaS 平台。

Zendesk
随着人工智能在自然语言处理方面的进步,品牌可以建立内部支持解决方案来处理咨询和解决问题,而不需要 Zendesk 这样的第三方平台。

****

我相信,Klarna 对人工智能的大胆押注预示着未来人工智能将在成本管理和盈利能力方面发挥更加重要的作用。该公司对人工智能工具的快速采用使其得以降低成本、增加收入,并为成功上市做好了准备。

对于规模较大的企业软件公司来说,Klarna 的例子既能给他们带来启发,也能使他们引以为戒。人工智能具有改变各行各业的潜力,但在实施时必须深思熟虑,并着眼于对员工和整个社会的长期影响。最终,Klarna 的人工智能之旅可能会成为其他公司的蓝图,但只有时间才能证明其快速转型的可持续性。

韦伯-史密斯的研究、数据和写作