No. 332: Risk and Religion of Peloton

AllyLoveYall

Today’s public markets seem to penalize the cults of personality. For an example, look no further than WeWork’s current debacle. In a sequence of events that may remind you of the ouster of Uber’s founder and CEO, WeWork also raised venture capital from Softbank and Benchmark. And the company’s board happens to be at odds with its own founder and CEO, just in time for a long-anticipated initial public offering.

It’s kind of stunning how quickly Adam Neumann has become a pariah. I have always thought the business was of questionable value. But it goes to show you how many people are ‘outcome over process.’ And the second the IPO stumbles, the knives come out.

Nick O’Brien

Two venture-backed companies with growing losses and questionable paths to profitability and only one of them looks to clear the bar to IPO. One possesses a cult of personality in Adam Nuemann, the other lords over a cult of fitness thanks to consumers like you. A notoriously fickle industry, Peloton has combatted the ebbs and flows of fitness micro-trends by recruiting and retaining top management. To Peloton, retention is the KPI.

Led by John Foley, Peloton is equal parts: quality of product, quality of programming, and quality of its users.  These users are Foley’s collective x-factor. It’s also a cohort that is more vulnerable than you’d think.

Peloton reported an impressive $915 million in total revenue for the year ending June 30, 2019, an increase of 110% from $435 million in fiscal 2018 and $218.6 million in 2017. Its losses, meanwhile, hit $245.7 million in 2019, up significantly from a reported net loss of $47.9 million last year. [1]

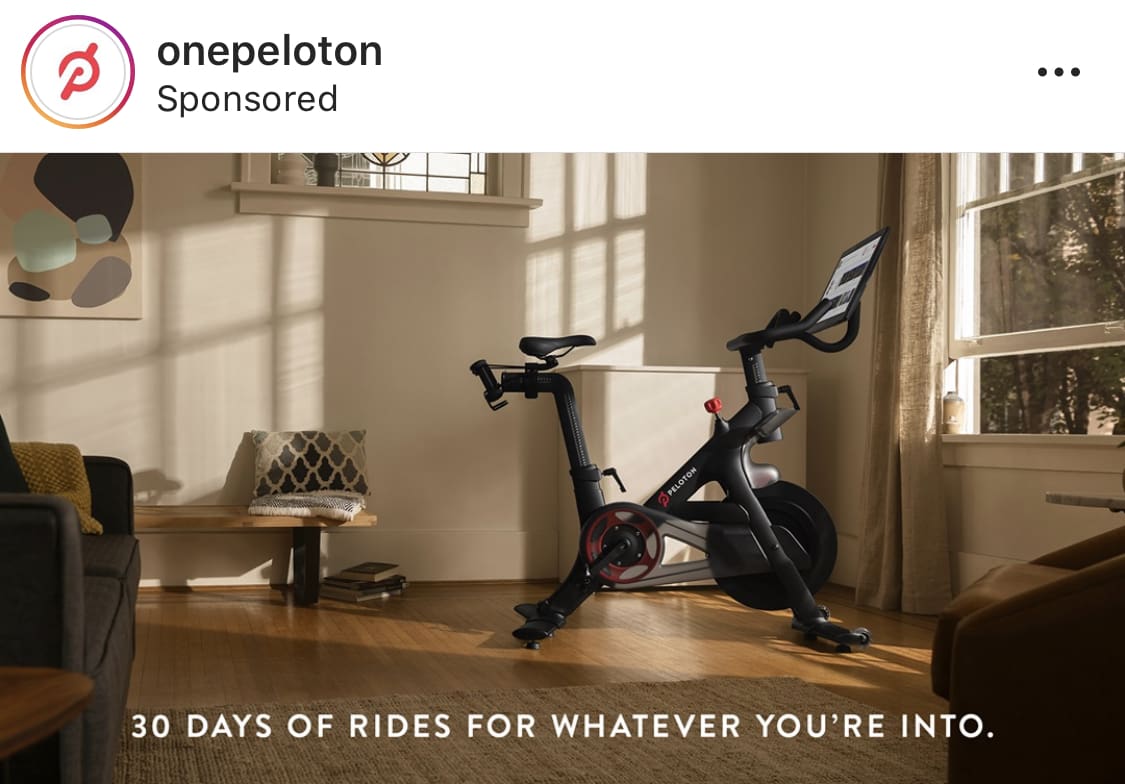
As Peloton nears IPO, the company has chosen to experiment with a new sales promotion. The expectation is that Peloton will bolster a few key metrics: new users, new subscriptions, and number of streams. By instituting the “30 day guarantee” found in informercial fitness products like NordicTrack and Bowflex, Peloton runs the risk of reducing lifetime value (LTV), increasing churn, and ostracizing the company’s highly motivated base by marketing to casual users and moving down market.

In the beginning, Peloton buyers were required to purchase the equipment in full. By partnering with Affirm, the consumer finance startup, the hardware / software company opened the doors to 0% financing over 36-48 months. This opened the product to middle class consumers without degrading LTV and average order value. This week, the company took one final step to reduce friction.  But while analysts laud the move as an enabler of growth, I’d argue that it may backfire.

Peloton is unlike anything that we have seen. For power users, the matte black cycle has become a source of inspiration, motivation, and even accountability. Personalities like Ally Love and Alex Toussaint have become household names. Just this summer, tennis legend Chris Evert made note of her apreciation for Ally Love during the broadcast of Tennis’ US Open. She noted that Love was “her spin instructor.” Before that moment, they’d never met in person. In my own household, I ocassionally ask my wife about her training sessions, “How was Alex, today?” She laughs every time; the running “joke” between us is that she refuses to stream another instructor.

The cult of Peloton isn’t anchored by the equipment. Rather, it’s the company’s human resources that remains the draw. And surprisingly, the company seems to be willing to manipulate it for short term growth.
IMG_0113As of the June filing of the the company’s S-1, Peloton showed over 511,000 subscibers and nearly 85 million cumulative sessions. To many users, it is an addiction of sorts. But the addiction is less a result of the physical product and more of a product of its efficacy. That takes time to materialize, much longer than a month. The hardware company’s marketing flywheel is perpetuated by the consumers who evangelize it. I’d argue that the time horizon to understand its value is closer to three months. A one month trial seems like a churn engine, not an acquisition funnel.

I’ve sold a number of colleagues on owning a Peloton of their own. This is commonplace, the S-1 suggests a high rate of word of mouth sales. In selling the product to peers, I’ve noted that the rides are painful but well worth the commitment. The hardware is beautiful and the augmented live stream is extraordinary. But it’s the sense of accomplishment and the commitment to the platform that I have found to be most valuable to the product’s brand equity. So yes, part of the lock-in stems from the commitment to ownership.

Understand the dualing strategies in the fitness industry:

  • Planet Fitness thrives on low motivation, short-term commitment, relatively minimal lock-in, and low attrition. The costs are so low, many members forget that they are still paying. This is by design. Costs are minimal because volume is key. If every member showed on the same day, there would be no space to exercise. Planet Fitness is a gym model.
  • Equinox thrives on high motivation, network effects, longer-term commitment, and low attrition. Costs are relatively expensive;  this cost prevents overcrowding and funds amenities. The network and those amenities keep customers coming back. Equinox is a club model.
S1
A high participation, high retention model resembling a club model.

At the height of the functional fitness craze, CrossFit’s growth was driven by high participation, efficacy, and peer-to-peer evangelism. Patrons from traditional gyms paid a premium to join one of 7,000 grungy, glorified garages and warehouses around the world. These customers were seeking a twisted enjoyment of challenging workouts (and the physical transformation that followed). But more importantly, they sought an active community. Peloton is shifting from the exclusivity of the club model to the inclusivity of the gym model. And this is where things become trickier for Peloton. The new pricing strategy conflicts with the longterm viability of its market position.

Nothing happens in a month

The 30 day trial promotion has been widely reported in publications like Bicycling Magazine and Shape.

This new offer is a clever way for the brand to give potential long-term customers a true taste of the bike experience and the wide variety of workout classes. For you, it’s a great way to try before you buy. [2]

This messaging conflicts with many of its value propositions. If I had to guess, it was likely a point of conflict within the c-suite. The company’s corporate structure is unique. It has nine members in that c-suite. Yet, a chief of marketing (CMO) is not one of them. It’s one example of an unfortunate trend in consumer retail.  After three years as PepsiCo’s senior brand manager, Carolyn Blodgett left a short stint with New York Giants organization to become Peloton’s senior marketer. As an SVP, it’s likely that she reports to the Chief Revenue Officer (Tim Shannehan) or the Chief Content Officer (Jennifer Cotter).

In this way, the lack of a singular vision may play a role in Peloton’s decision to test a trial system. While pricing incentives aren’t rare in SaaS sales or the marketing of physical goods, they do tend to be the tip of the spear for brands seeking to introduce further discounts and incentives. And they spell trouble for a company that will be largely defined by the best practices of fitness clubs and software-based network effects. Peloton will have a hard time explaining the supremacy of its product as the trial periods grow from one month to three or four. Or worse, when the $2,300 cycle that you paid for is on sale for $1,200 over the holiday season. Pricing incentives are a slippery slope.

With marketing and real estate costs eating into Peloton’s net profitability, the writing is on the wall.  The company believes that growth costs have become too expensive and with a $1.2 billion IPO in waiting, the story of efficient growth may determine the company’s viability over the next two quarters. Unfortunately, this may be a short-sighted injection of growth.

Like WeWork’s attempt to silence its cult of personality, Peloton risks weakening its cult of fitness. Only one of these seems intentional. It’s unclear whether Peloton’s management fully understands the risks involved. The company’s strength is two-pronged: its on-screen talent and its cult-like early adopters. The market may reward Peloton for leaning on new methods of influence and acquisition. However, their management won’t begin to see the unintended effects of mass adoption (and increased churn) until its marketing flywheel begins to sully.

In the unfortunate case of that happening, Peloton will become just another in-home cycle with a screen. And in that case, consumers will see a lot more of the words Peloton Infomercial 20:00 in their cable guide’s lineup. And that’s no place for a religion to be sold.

Read the No. 332 curation here.

Report by Web Smith | About 2PM

Additional reading: Peloton vs. Tonal (Member Research)


No. 331 Part One: As Seen on TV

2PMAsSeenAs

In a private New York City dining room sat a few dozen executives across digital media and retail. Of them included companies like The Chernin Group, Cameo, Instagram, Barstool Sports, Stripe, Digiday, Seat Geek, theSkimm, Andie Swim, 2PM, and Zola. These companies ranged from venture-backed DTC brands to digital media companies that are valued well into the nine figures. Everyone had a particular problem to solve. We discussed industry-wide concerns to include: advertising efficacy, margins, scale, and sustainable growth.

On this night, Instagram wasn’t the center of the universe. At least not at first. A rarity given the social media giant’s surroundings. The moment that quieted the room wasn’t one devoted to the foretelling of a new marketing technologies, innovations, or hacks. Rather, it was an anecdote about traditional marketing channels.

Andy Khubani is the CEO of Ideavillage, a holdings company that pumps out well-researched, highly marketable “power brands.” Flawless, a hair removal system for women, was the brand name of his latest success.  A power brand tends to be asset-light, high growth, with high margins, manufacturing leverage, logistics prowess, and a sustainable competitive advantage. 

In 2018, he sold Flawless to Church & Dwight for $450 million (or 2.5 times revenues). In year two, his company grossed $180 million with a 30% EBITDA margin, according to a March 2019 press release. 

To scale the company, he used a traditional style of advertising and promotion. 

Backed by print advertising, ads on New York City taxis and blogging campaigns— to go with the full-scale DRTV campaign— Flawless has quickly become a top-selling retail beauty product in As Seen On TV sections and in-line beauty and shaver departments. [1]

In a room full of digital advertisers, platforms, and merchants – everyone was likely asking themselves the same question: how did he reach critical mass so quickly? With no outside capital raised and no performance marketing spend alloted, Khubani built a brand worth nearly half of a billion dollars in just two years. Absolutely no one in DTC is doing that. The most recent acquisition was of Oars & Alps for $20 million. They raised nearly $7 million. This week, Tristan Walker recorded his episode of “How I Built This.” He sold his company to P&G for less than $40 million. Greats Brand sold to Steve Madden for less than $30 million. I could go on.

Khubani’s magnitude of exit is incredibly rare in the DTC space. Since 2007, fewer than seven DTC brands have exited for a price as high as $450 million. Flawless’ early profitability contrasts most in an industry where LTV:CAC optimization is a law akin to the Old Testament. The widely held consensus is to spend heavily now, despite a lack of profits, to earn a customer for a lifetime. This method extends the horizon and heightens the capital requirement but it also absolves executives of the near term pressure to achieve scale early. The LTV:CAC optimization theory is one that I have found to be disingenuous at best. Markets change, competition arises, technology improves, and consumer sentiments shift with the gusts of pop culture and the zeitgeist.


From No. 310: The DTC Playbook is a Trap

As long as DTC brands attempt to follow what’s been done before them, you too should be skeptical of the industry. Many investors seem to look for a DTC Playbook to hand their portfolio companies. As if to say, “Here is how it’s done. Now execute the game plan!” But it’s likely that it will never be that way. As digital-natives begin competing in traditional retail’s territory, heritage brands should serve as a reminder. They had unique paths to critical mass, very few encountered the predictability that the DTC era seeks.


There seems to be two considerations for challenger brands of today. Either optimize for the early exit or settle into growth over a 15+ year horizon. Venture capital doesn’t typically compel either outcome. It is the pursuit of the uncomfortable “in between,” the 5-10 year horizon, that may be a root of DTC’s liquidity problem. For many companies in that space, there is a lot to learn from power brands. The ones that scale fast and exit. Flawless is but one of many.

As Seen On TV / As Seen In Stores

Over the past weeks, several data points suggested that the days of DTC playbook are long past. As traditional brands adopt the technologies and the web-first approaches to growth, many of them have widened their advantages between their own companies and the challenger products vying for the same shelf space.

eCommerce is a tremendously challenging, frequently unprofitable business. It also doesn’t take into account how much consumers still want to be in person with brands and products and people.

Andy Dunn

In an interesting breakdown by Yotpo VP Raj Nijjer, the retail executive presented a few surprising metrics [2]: Sealy Mattress’ direct to consumer sales surpassed Casper’s total revenue in 2018 despite Casper taking the mindshare of online retail advertising and consumer chatter. He also noted that Madewell: a brand that is primarily driven by physical real estate, traditional advertising, and traditional brochures – will do $534 million through online retail channels.

[Dunn] said that, in the case of Bonobos, the brand’s “most profitable business” today is its partnership with Nordstrom. Bonobos now also boasts 66 brick-and-mortar stores known as “guides shops.” [3]

When Khubani detailed how he built Flawless into a relative powerhouse, he made it clear that part of the problem with the DTC era is the inability to truly compel purchases. In short, few DTC executives know how to actually sell. Many are dependent on the superficiality of the impression as a metric rather than the depth found when executives target more than a consumer’s eye balls.

I don’t really like digitally native vertical brands. What gets me excited are brands that are really strong and direct-to-consumer, but also have got omni.

Andy Dunn

He believes that he has it down to a science. And it’s hard to argue that he’s wrong. When the typical DTC brand or digital media operator considers the word “targeting”, it instills a sense of modernity. “Television ads are inferior to the quantitative capabilities found with Facebook and Instagram,” a refrain that you will hear from the typical media agency founder. Khubani suggested that brand managers should reconsider the definition of “targeting.” While television advertising espouses a broader approach to reach, it targets a different part of the consumer.

Screen Shot 2019-09-16 at 3.32.01 PMThe consistent approach to an Instagram or Facebook ad is to engage the eyes. We visit the app to mindlessly consume images. Rarely do we stongly recall what we’ve seen after we’ve left the app. We don’t tweet about it; we rarely talk about it. That collection of targeted, inline advertisements are calculated impressions. They are visuals that spark a mental consideration by capturing a consumer’s eyes – if only for a second. It’s why you see scrolling .gifs of coupon codes, diagrams with price incentives, or photos of marked with fabric qualities. On social, brand advertising is often a science and not an art. Brand managers are working to compel the sale through the logic of price and comparison. Television is different. It inspires the heart. When we consume our favorite show, we talk about and we spread the joy of consumption through social channels.

On this night, Instagram wasn’t the center of the universe. At least not at first.

Just as a physical billboard that is uploaded to Instagram or Twitter becomes a social ad; a consumer good that we discover on television accelerates the growth curve through social and distributive channels. Those crude “As Seen” advertisements have been known to compel purchases so well that stores devote aisles to the category of products. But in this era, the benefit is even greater for brands like Flawless. Early traction, often fueled by television can equate to wider physical and online distribution. This perpetuates affiliate deals, social influencer participation, and earned media. These are all key performance indicators of DTC marketing traction for many brands.

The Two Andy’s: Dunn and Khubani

It’s been rumored that for that $180 million in 2018 sales, Flawless paid for less than $2 million in traditional advertising. With a $450 million exit + incentives, the return on advertising was clearly remarkable in size and in velocity. But surprisingly, that wasn’t the key takeaway.

As DTC brands improve their ability to sell, they will advertise more like the original direct brands, ones that intrigued consumers through their televisions. These brands compelled the sale via phone, computer, or that distinct shopping aisle in Walmart or Target.

The report, which synthesizes information from 125 top DTC brands representing 52 different categories, found that DTC brands included in the study spent 60% more on television ads in 2018 than they did in 2017, totaling $3.8 billion in television ad spend last year.  [4]

Consumers are due to see more television ads from brands like Away.  But for some categories of products, the production style will shift away from brand statement and towards the longform style of selling that you’ll only find on TV. This new era of retailer will be slow to use television in the longform manner that marketing executives have mastered. The traditional television demographic may not be suitable for many new brands or their products.

But, for certain categories, marketing and distribution strategies will continue to evolve in that direction. These will include many of the cues found in those hard-selling infomercials.  There are new tools available to brands that are looking to adopt more of the merchant’s DNA. As television, billboard, and QVC-like platforms feature more DTC brands, these selling strategies will make their way to digital-first platforms.

In this way, Andy Khubani’s thoughts were prescient. The direct-to-consumer industry commonly appeals to consumers through two styles of media: (1) the lofty brand statement or (2) the coupon code value proposition. The style of advertising that drove Flawless from $0 to $180 million was a combination of both styles, designed to carry the potential customer from discovery, to intrigue, to conversion, to evangelist. As Andy Dunn noted, digitally natives brands will continue to struggle without an omnichannel approach to growth.

Brands are using traditional retail sensibilities to achieve half billion dollar exits by year three. Nearly $534 million in DTC revenue by Madewell, a J. Crew-owned private label headed towards IPO. Walmart building their own brands rather than acquiring digitally natives. And the godfather of the term “DNVB” noting that being a digitally native is now a disadvantage.

In the coming months, DTC brands will build around the aforementioned style of television advertising. They will test it on platforms like Instagram, ads will playfully mimic the cadence and tone. They’ll build the processes out on newer platforms tailor-made to achieve efficiently scalable levels of reach and engagement. The two Andy’s seemed to be advocating for similar best practices. By 2018, the cloud-based technologies commonly used by online-first brands had been widely adopted by legacy retailers. For challenger brands to regain their competitive advantages, they should look to the proven advertising and distribution strategies of the old guard. And then, they should make them their own.

Read the No. 331 curation here.

Report by Web Smith |About 2PM

Memo: Gen Z Arbitrage

For those with Android-based smartphones in 2010, you may recall a fear of missing out. For iPhone owners who had access to a fledgling startup called Instagram, they made sure to remind you that your phone was incapable of using the software. Nothing matched the aesthetic or network effects of the photo-sharing platform for the rich kids. The fear of missing out moved many to leave Android for iOS. For those who couldn’t, Apple’s products lived – rent free – in their minds until they too had the opportunity to own their very own iPhone. This was Apple’s strategy and there’s a chance that it wouldn’t have been executed without John Doerr’s vision for Steve Jobs and his app store.

In 2008, Kleiner Perkins Chairman and partner John Doerr recognized the transformative influence that the iPhone’s launch would provide for the mobile software industry. As the story would go, Steve Jobs privately discussed the prospects of the iPhone’s fledgling app store with Doerr. Jobs originally viewed the marketplace as a private entity, one that would remain under the complete control of Apple’s management. Doerr had different plans. He believed that by outsourcing the development and marketing of apps to third party teams of software engineers, Apple would build an effective moat around their mobile operating system.

Eventually, Jobs obliged. He agreed with the ecosystem lock-in potential of tens of thousands of software engineers building products for Apple’s new mobile operating system. Managed by Kleiner’s Matt Murphy (now with Menlo ventures), the $100 million iFund launched in 2008 and was later doubled to $200 million. Kleiner’s commitment to the burgeoning mobile software industry directly and indirectly impacted consumerism forever. Numerous venture firms identified the massive opportunities that mobile applications would provide and billions in venture capital followed suit.

Leading iPhone apps in the Apple App Store in the United States | Source: Priori Data

Just as Kleiner’s pioneering iFund once inspired an arbitrage that even Steve Jobs couldn’t have anticipated, the iPhone is once again at the center of an equally critical opportunity. As of March of 2019, the iPhone had an installed base of around 193 million in America. An astounding number given that the United States population is estimated to be around 372 million. By 2021, 45.4% all Americans are projected iPhone users.

China already is outpacing the U.S. and much of the developed world in mobile payments, and a new digital currency that authorities say would be like cash and accepted everywhere would put China miles ahead in the currency space. [1]

Apple’s app store helped to solidify the iPhone as perhaps the most pivotal consumer product of the early 21st century. One that powered transportation, communication, advertising, and global commerce. But nearly 12 years later, America’s commerce adoption still lags behind other global powers. Consider China, a country that achieved 73.6% digital shopper penetration in 2018. Mobile payments continue to drive the vast majority of online retail activity in the Asian country.

The rise of mobile payments in China

As a result, over 35% of all retail sales in China are done through online retail channels. In the United States, online retail adoption hovers at 12%. Mobile payments are commonplace throughout China across age, geography, and economic status. The ability to buy and sell goods online is so commonplace that Generation Z is the leading market for online luxury shopping in China. This has been bolstered by explosive growth in mobile payments over the past five years, a transaction volume that reached $45.1 trillion in 2018. According to the People’s Bank of China, this figure grew 28x in five years. It was largely driven by a cultural shift that saw China’s youth (Generation Z) empowered to transact for goods and services across China’s online retail and media ecosystem. According to Chinese media, proximity payment platforms Alipay and WeChat account for nearly 90% of the transactions. In America, there are 61.9 million proximity payment users, transacting just 113.79 billion in retail sales according to Statista’s 2019 data.

The Retail Arbitrage Ahead

Generation Z is the largest, youngest, most ethnically-diverse generation in American history. With over 82 million members, this cohort comprises over 27% of the US population.

While China’s Generation Z is more active in the purchase of consumer goods than their American counterparts, a snapshot of Gen Z’s current buying power would likely surprise you. TransUnion studied the credit market for buyers between the ages of 18 and 23 between Q2 2018 – Q2 2019. In that year, this consumer cohort accounted for 319,000 mortgages, 746,000 personal loans, 7.75 million credit cards, and 4.37 million auto loans.

Penetration rate of online luxury shopping in China | OC&C

Nearly 27% of Americans (and growing) fall within the birth years of Generation Z, a demographic that is of critical importance to legacy retailers and DTC brands, alike. In China, a country often measured as a leading indicator for American commerce trends, Generation Z leads in luxury retail adoption. In America, Generation Z is awaiting the opportunity to buy with the frequency of Millennials and Generation X. The data suggests that their consumer activity will trump that of previous generations. While Millennials prefer DTC brands by a margin of just 4% over traditional retailers, Generation Z prefers these online-born brands to their legacy counterparts by over 40-45%.

Gen Z, the group born between the mid-1990s and 2010, is already known for its financial literacy. More mature and pragmatic than its older millennial forbearers, the cohort is savvy with both finances and technology, survival skills that members gained after watching siblings and parents suffer through the 2008 recession. [2]

These are the brands that they’ve grown up with on social channels used over their iPhones: Snapchat, TikTok, WhatsApp, Instagram and others. The DTC arbitrage in 2020 and beyond will be closely tied to mobile payments. The growing adoption of CashApp, Venmo, and teenage banking programs like Current may begin to help Americans close the gap between the US v. China mobile payment adoption rates. At the center of this activity is Apple Pay, the tool with the most potential to influence Gen Z’s retail habits.

No Title

Online retail / DTC arbitrage:2008: Shopify over custom builds2012: Warby’s PR playbook2014: Facebook advertising2016: Key affiliate partnerships 2018: Selling the first $3-5M w/o ads

Generation Z is as technologically dependent as Generation X is physically independent. Whereas all day bicycle excursions and unannounced sleepovers were a fixture in the 70’s and 80’s, that is much less so today. The meeting places and opportunities are increasingly presented in the form of digital layers. In that way, millennial parents have had to come to terms with moderating a new era of independence. Fewer drivers licenses and cars, more subscriptions and teen banking accounts.

Alexis is a middle school-aged girl in the American Midwest. An A student, athlete, and all-around great kid, she tends to earn extra privileges from time to time. Equipped with her Apple Pay-enabled iPhone, her love of TikTok and Instagram, her fascination with Glossier and Athleta, and a bit of granted independence – she’s transacted $113.41 with Glossier and Athleta’s cart in the first three quarters of 2019. The limiting factor has been her access to funds, a constraint that Apple will likely account for by offering a peer-to-peer subscription product. Apple Pay provides an independence that Americans are still dueling with. But that’s evolving. Parents are trusting of their children maintaining cash balances on their mobile phones, especially if they can easily monitor spend and availability.

If you ask the founders of Warby Parker how the team scaled so quickly, they may mention the low costs of Facebook and Instagram ads at the time. They may cite the savvy public relations work that led to that magnanimous GQ article. This moment was responsible for the  initial sell-through of their first run of prescription glasses.

70% of Gen Z has made in-app mobile payments in the last year. More than any other generation. [3]

From time to time, there are technological and economic advantages that lift the brands that are prepared for the moment. For direct to consumer brands, a category of brands that Gen Z prefers over traditional retail, there is an opportunity to shorten the marketing funnel by appealing to a generation of consumers that have been written off by the incumbents in retail. Traditional brands are marketing to the parents of America’s youth rather than directly communicating to a demographic that could benefit them. The data suggests that as Apple Pay’s adoption rates continue to improve, Gen Z will become the primary consumers of the goods that have, so far, been marketed to Millennials and Gen X members.

Year 2020

We underestimate the significance of the Apple card being used as a function of the Family Share, a program that allows Apple users to share access to digital products and assets with their families. The moment that ‘Gen Z’ is capable of spending (while accountable to their parents) is the moment that 27% of American consumers, with a preference for DTC brands, floods the market. This is the potential arbitrage that awaits for this era of retail.

And in this way, this small shift in corporate strategy resembles the magnitude of moment that John Doerr was responsible for. Either Apple will build a native function that allows guardians to ‘subscribe’ and account for potential monthly allotments to their dependents. Or a third-party solution will be engineered by an outside developer. Of all the mobile payment solutions available to consumers, it is Apple that sits at the trusted intersection of family and finance.

The Apple card is a platform that few have recognized. It’s also another lock-in opportunity, perhaps the first of the Tim Cook era. With few exits, low multiples, and increasing customer acquisition costs – the weakening viability of the DTC ecosystem has been difficult for operators and investors alike. By accelerating Gen Z’s path to becoming independent consumers, Apple stands to benefit during a time where the Cupertino-designed hardware is as commoditized as ever.

And like Silicon Valley benefited from Apple’s democratization of the app store in 2008, this era of consumer brands will stand to benefit from democratization of consumerism within the home. Our Gen Z daughters want Balm Dotcom.

Read the No. 330 curation here.

Research and Report by Web Smith | Edited by Tracey Wallace | About 2PM